

Week of October 16, 2026
The Week at a Glance:
Healthcare shares diverged from the broader growth-stock selloff. Pharma and medical equipment advanced, while biotechnology declined. Two IPOs raised $350M, and strategic activity favored surgical products, digital pathology, and targeted drug development. The distinction this week was between investors seeking established earnings and those prepared to fund specific clinical risks.
Defensive Healthcare Outperforms: Pharma and medical equipment gained as the Nasdaq fell 4.5%. Biotechnology lagged despite several successful financings.
New Issues Attract Capital: Two biotech IPOs raised $350M, with both issuers trading above their offer prices. Follow-on and private financing activity was concentrated in a handful of companies.
Acquirers Extend Existing Franchises: STERIS and Agilent pursued acquisitions that add products and software to established customer relationships. Pharma continued to license targeted programs, with most consideration deferred.
Markets Overview
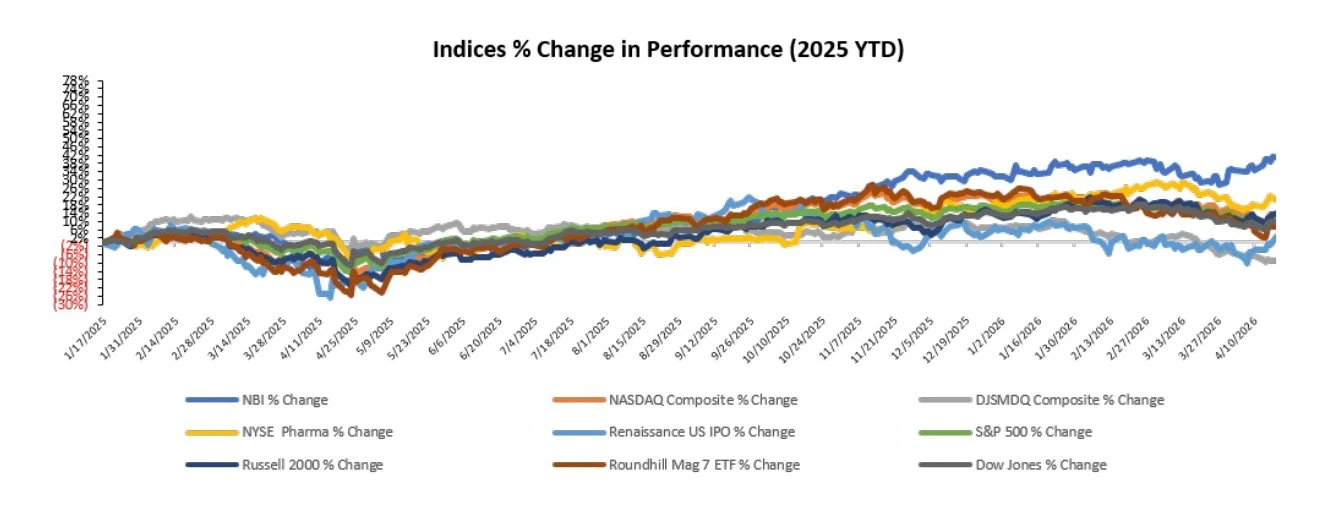
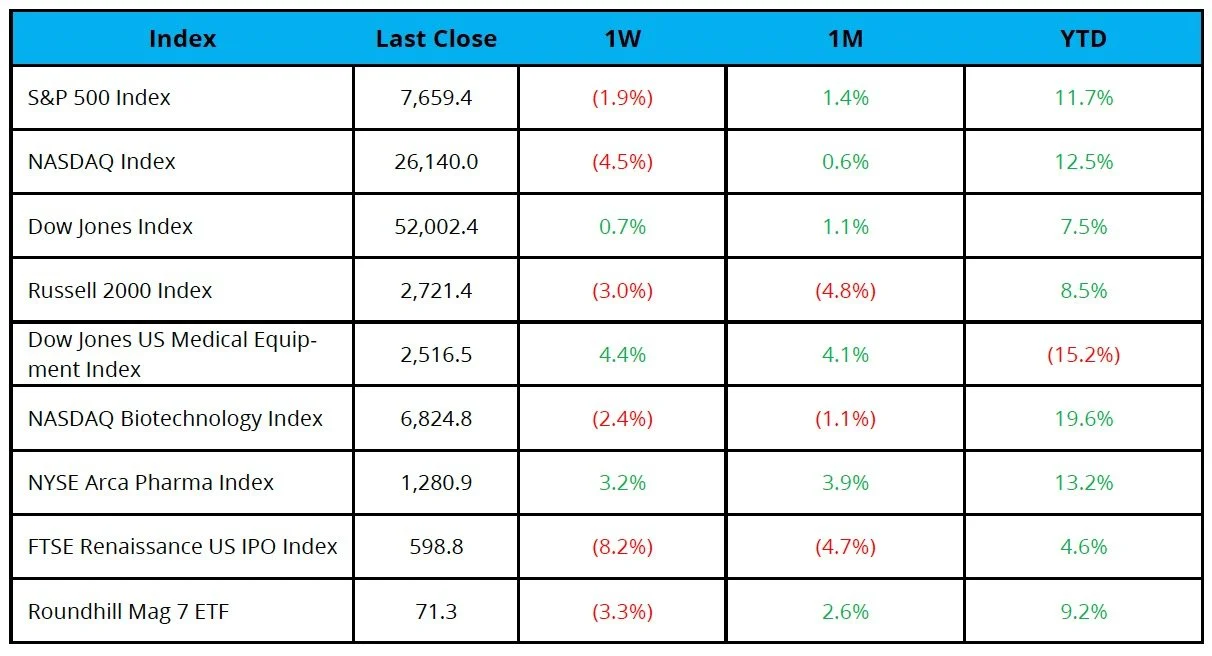
The Nasdaq fell 4.5% and the S&P 500 declined 1.9% last week; the Dow rose 0.7%.
The rotation was pronounced: Pharma gained 3.2% and medical equipment 4.4%, against a 2.4% decline in the NBI. Liquidia rebounded after resolving patent litigation, while Syndax fell on a failed IPF study. The contrast underscores the influence of individual catalysts within biotech.
The NYSE Pharma Index rose 3.2%, while the NBI declined 2.4%.
Notable change in share price:
Liquidia (NASDAQ: LQDA): Shares rose 26.6% after announcing a $380.7M settlement with United Therapeutics resolving six lawsuits and securing continued commercialization of YUTREPIA in pulmonary arterial hypertension (PAH), partially recovering from a 57.2% decline on September 30 following an adverse patent ruling that threatened the drug’s commercial outlook
Syndax Pharmaceuticals (NASDAQ: SNDX): Shares fell 15.7% after its Phase 2 MAXPIRe trial of axatilimab in idiopathic pulmonary fibrosis (IPF) failed to meet its primary endpoint of slowing lung function decline, prompting the Company to discontinue development in IPF while continuing to advance axatilimab in chronic graft-versus-host disease
Sources: Pitchbook, Biomedtracker, and CapIQ
Equity Markets
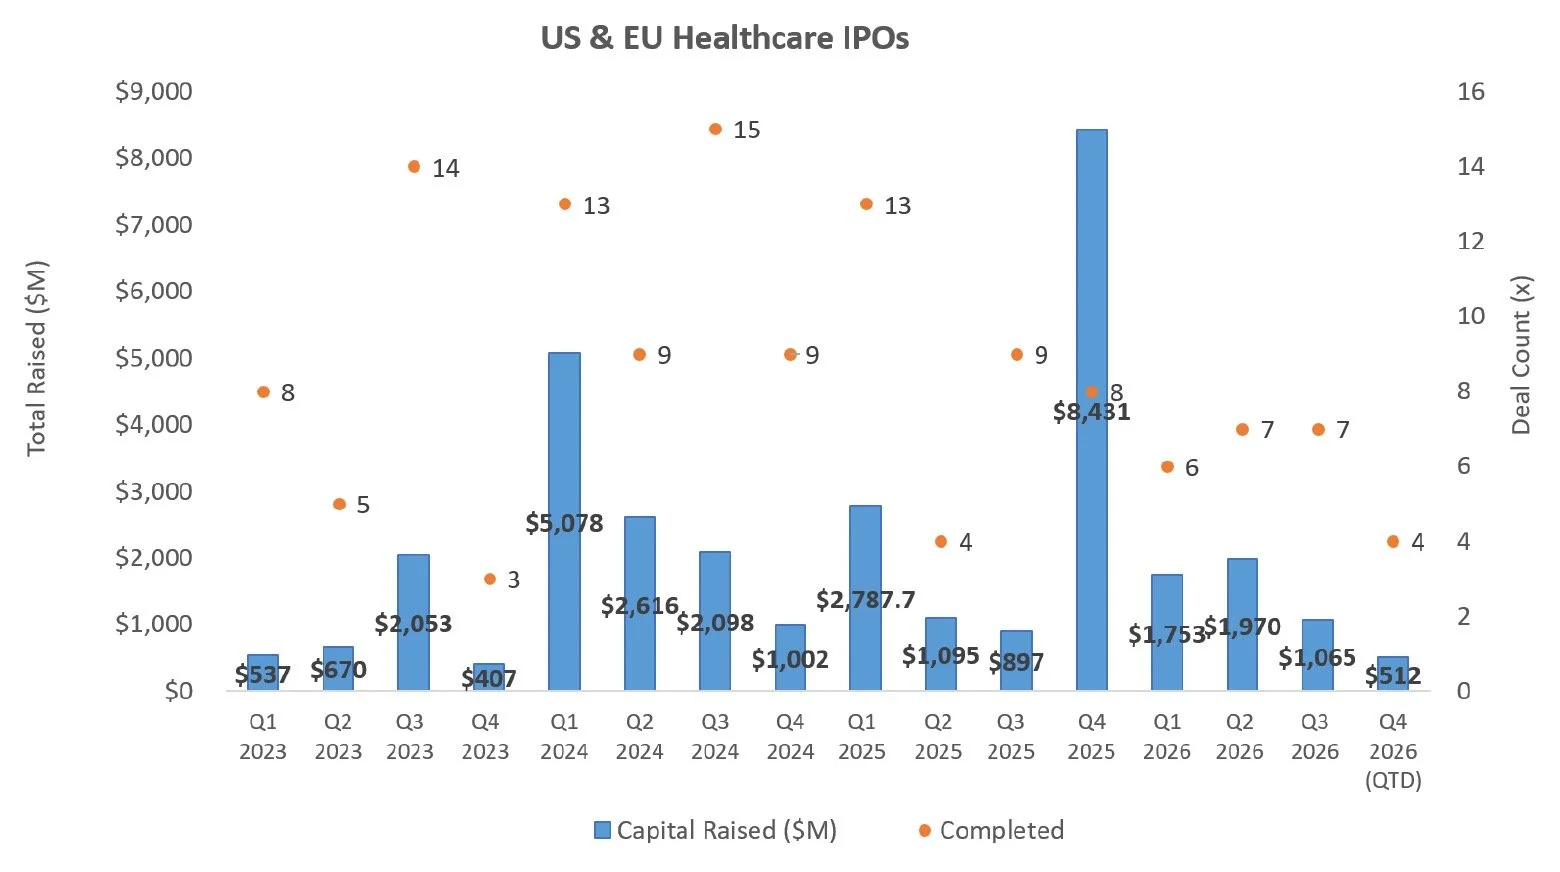
IPO
The IPO window held despite the growth-stock selloff, with two healthcare IPOs priced last week totaling $350M. Both issuers attracted demand, but aftermarket performance and the next wave of pricing will provide a better test of its depth.
Iambic Therapeutics (NASDAQ: IAM) raised $150M to advance lead HER2 inhibitor IAM1363 toward potential registrational development, advance KIF18A inhibitor IAM217 and dual CDK2/4 inhibitor IAM-C1 through early clinical development, and support its AI-enabled drug discovery platform, working capital and general corporate purposes
City Therapeutics (NASDAQ: CTY) raised $200M in an upsized deal to advance CITY-FXI through Phase 1 and Phase 2 development in thromboembolic disease, advance CITY-RBP4 into clinical development for Stargardt disease and geographic atrophy, progress CITY-TFR2 for anemia of chronic disease, and support its broader RNAi platform and discovery programs
Source: CapIQ
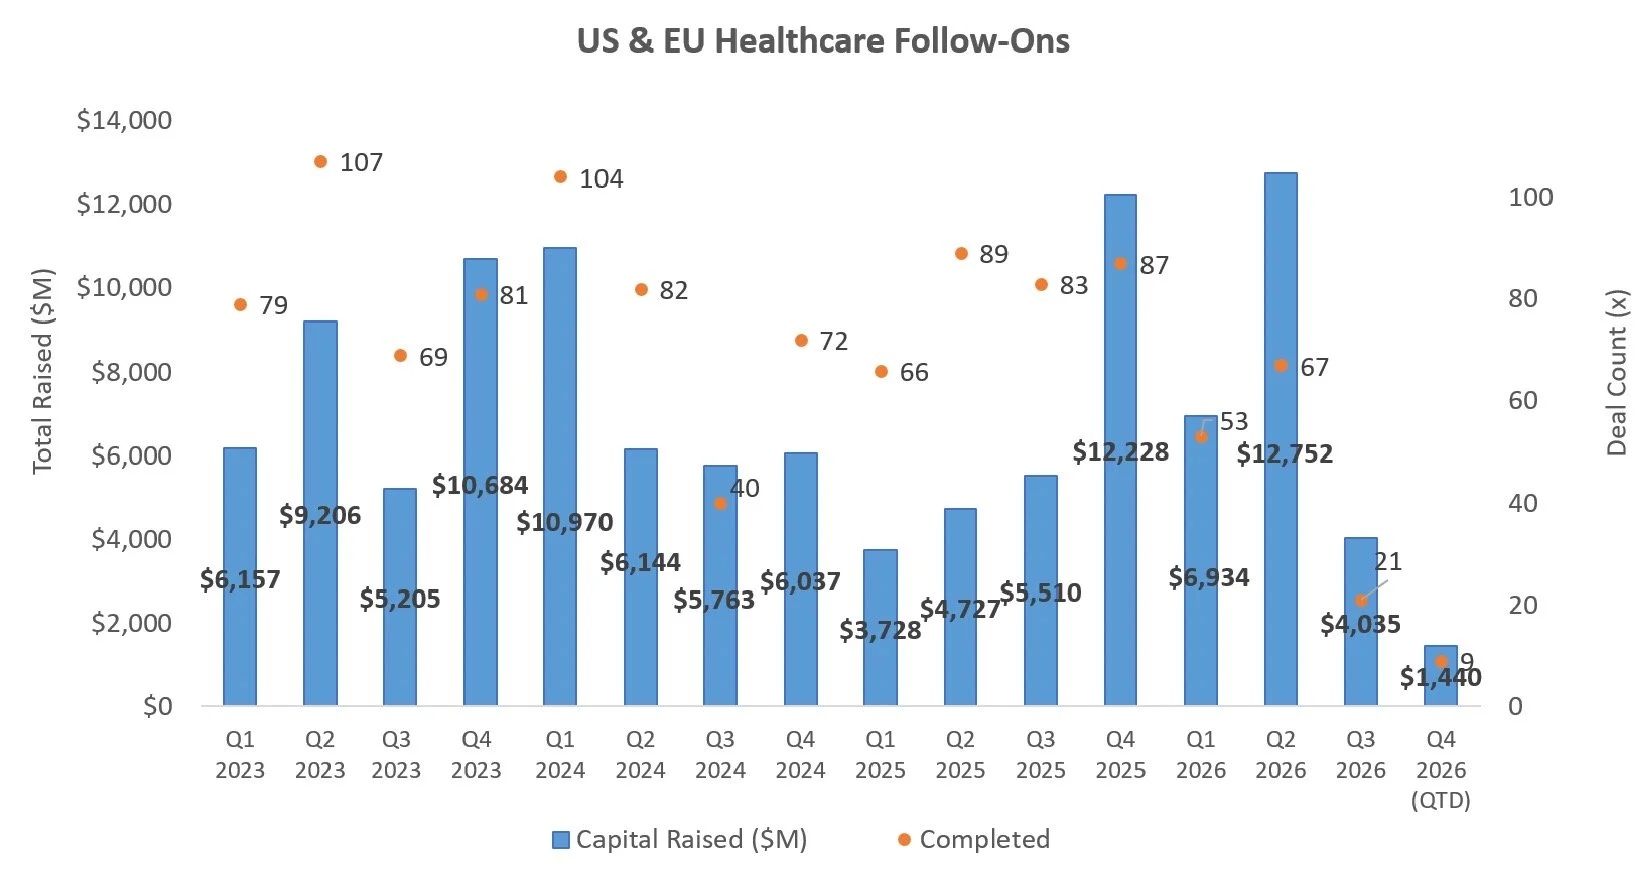
Follow On
There were two follow-on offerings last week totaling approximately $450M in proceeds, both financing defined development programs, the smaller issuer being a point to watch.
Verastem Oncology (NASDAQ: VSTM) raised $250M in an underwritten public offering to fund continued clinical development of its oncology pipeline, including VS-7375, its oral KRAS G12D inhibitor being developed across pancreatic, lung, and other RAS/MAPK-driven cancers, as well as working capital and general purposes; the offering consisted of common stock and pre-funded warrants
Recursion Pharmaceuticals (NASDAQ: RXRX) raised $200M in an oversubscribed follow-on offering to advance its highest-priority clinical programs, including REC-4881 in familial adenomatous polyposis and REC-1245 in solid tumors, support its partnered and internal pipeline and extend its cash runway into 2029; participating investors included Janus Henderson Investors, Invus, Longaeva Partners, ARK Invest, and Driehaus Capital Management, alongside other healthcare-focused investors and mutual funds
Source: Biomedtracker
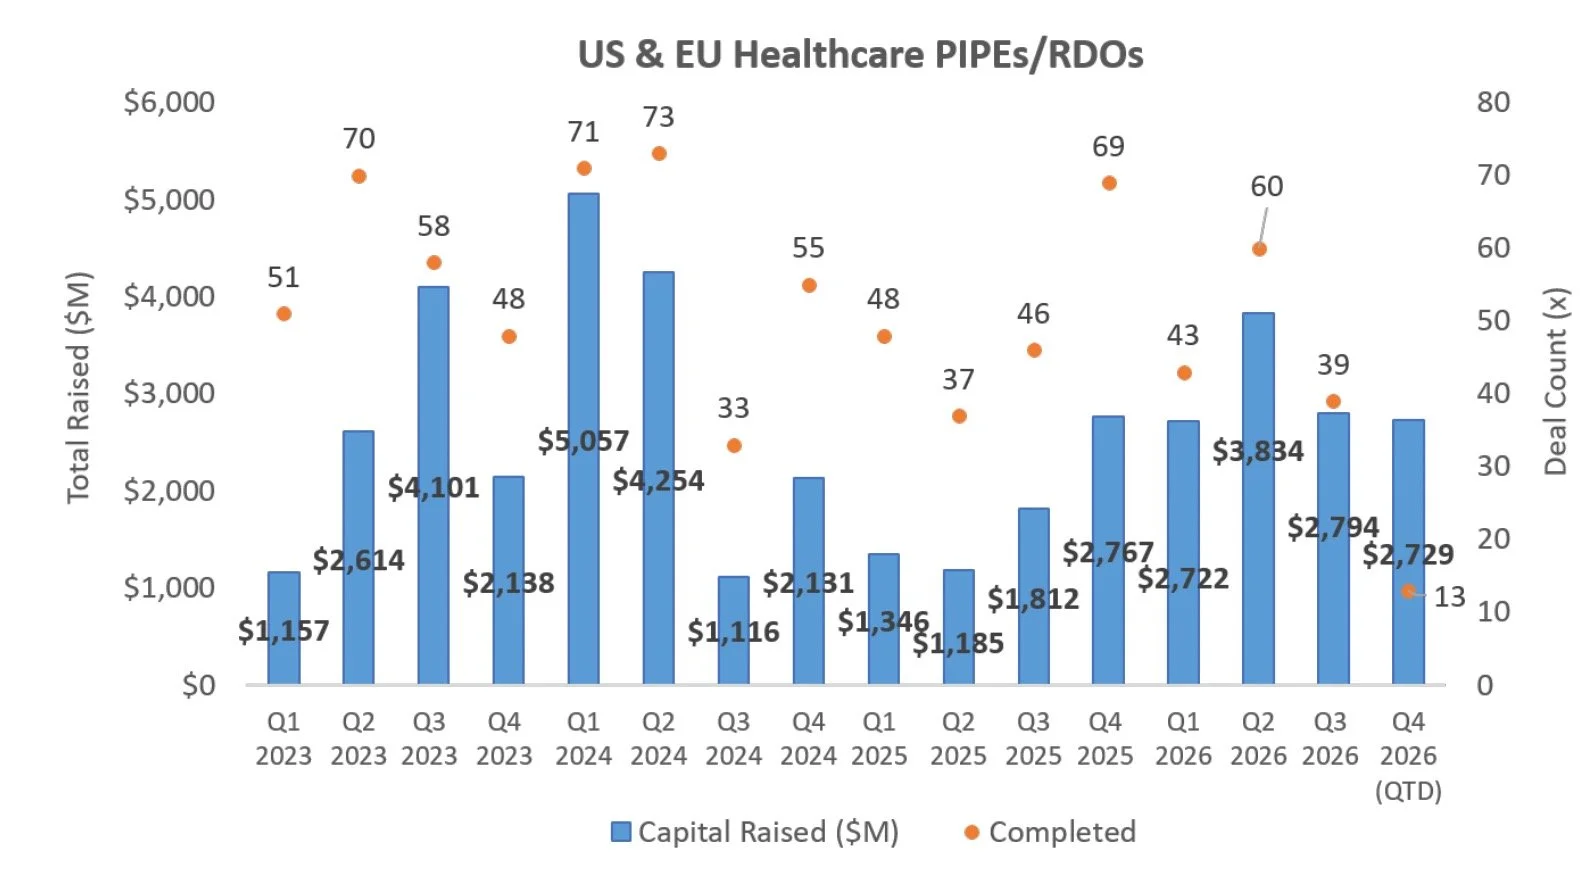
PIPE/RDO
There were four PIPEs / RDOs announced last week totaling approximately $563M, concentrated in Alaunos and First Tracks.
Alaunos Therapeutics (NASDAQ: TCRT) raised $350M in an oversubscribed PIPE, concurrent with its acquisition of Velaris Therapeutics, to advance Velaris’ pulmonary hypertension pipeline, including VLR199, through multiple clinical proof-of-concept milestones and provide expected cash runway into 2029; the financing was led by Fairmount with participation from Venrock Healthcare Capital Partners, T. Rowe Price Investment Management, Wellington Management, Janus Henderson Investors, Access Biotechnology, BB Biotech, Perceptive Advisors, Sirenia Capital Management, and ADAR1 Capital Management, among others
First Tracks Biotherapeutics (NASDAQ: TRAX) raised $200M in a private placement to support general corporate purposes, including continued clinical development of ANB033, its CD122 antagonist being developed in celiac disease and eosinophilic esophagitis; participating investors included Affinity Asset Advisors, First Light Asset Management, Sirenia Capital Management, TCGX, Trails Edge Capital Partners, and Vestal Point Capital, alongside another life sciences-focused institutional investor and multiple mutual funds
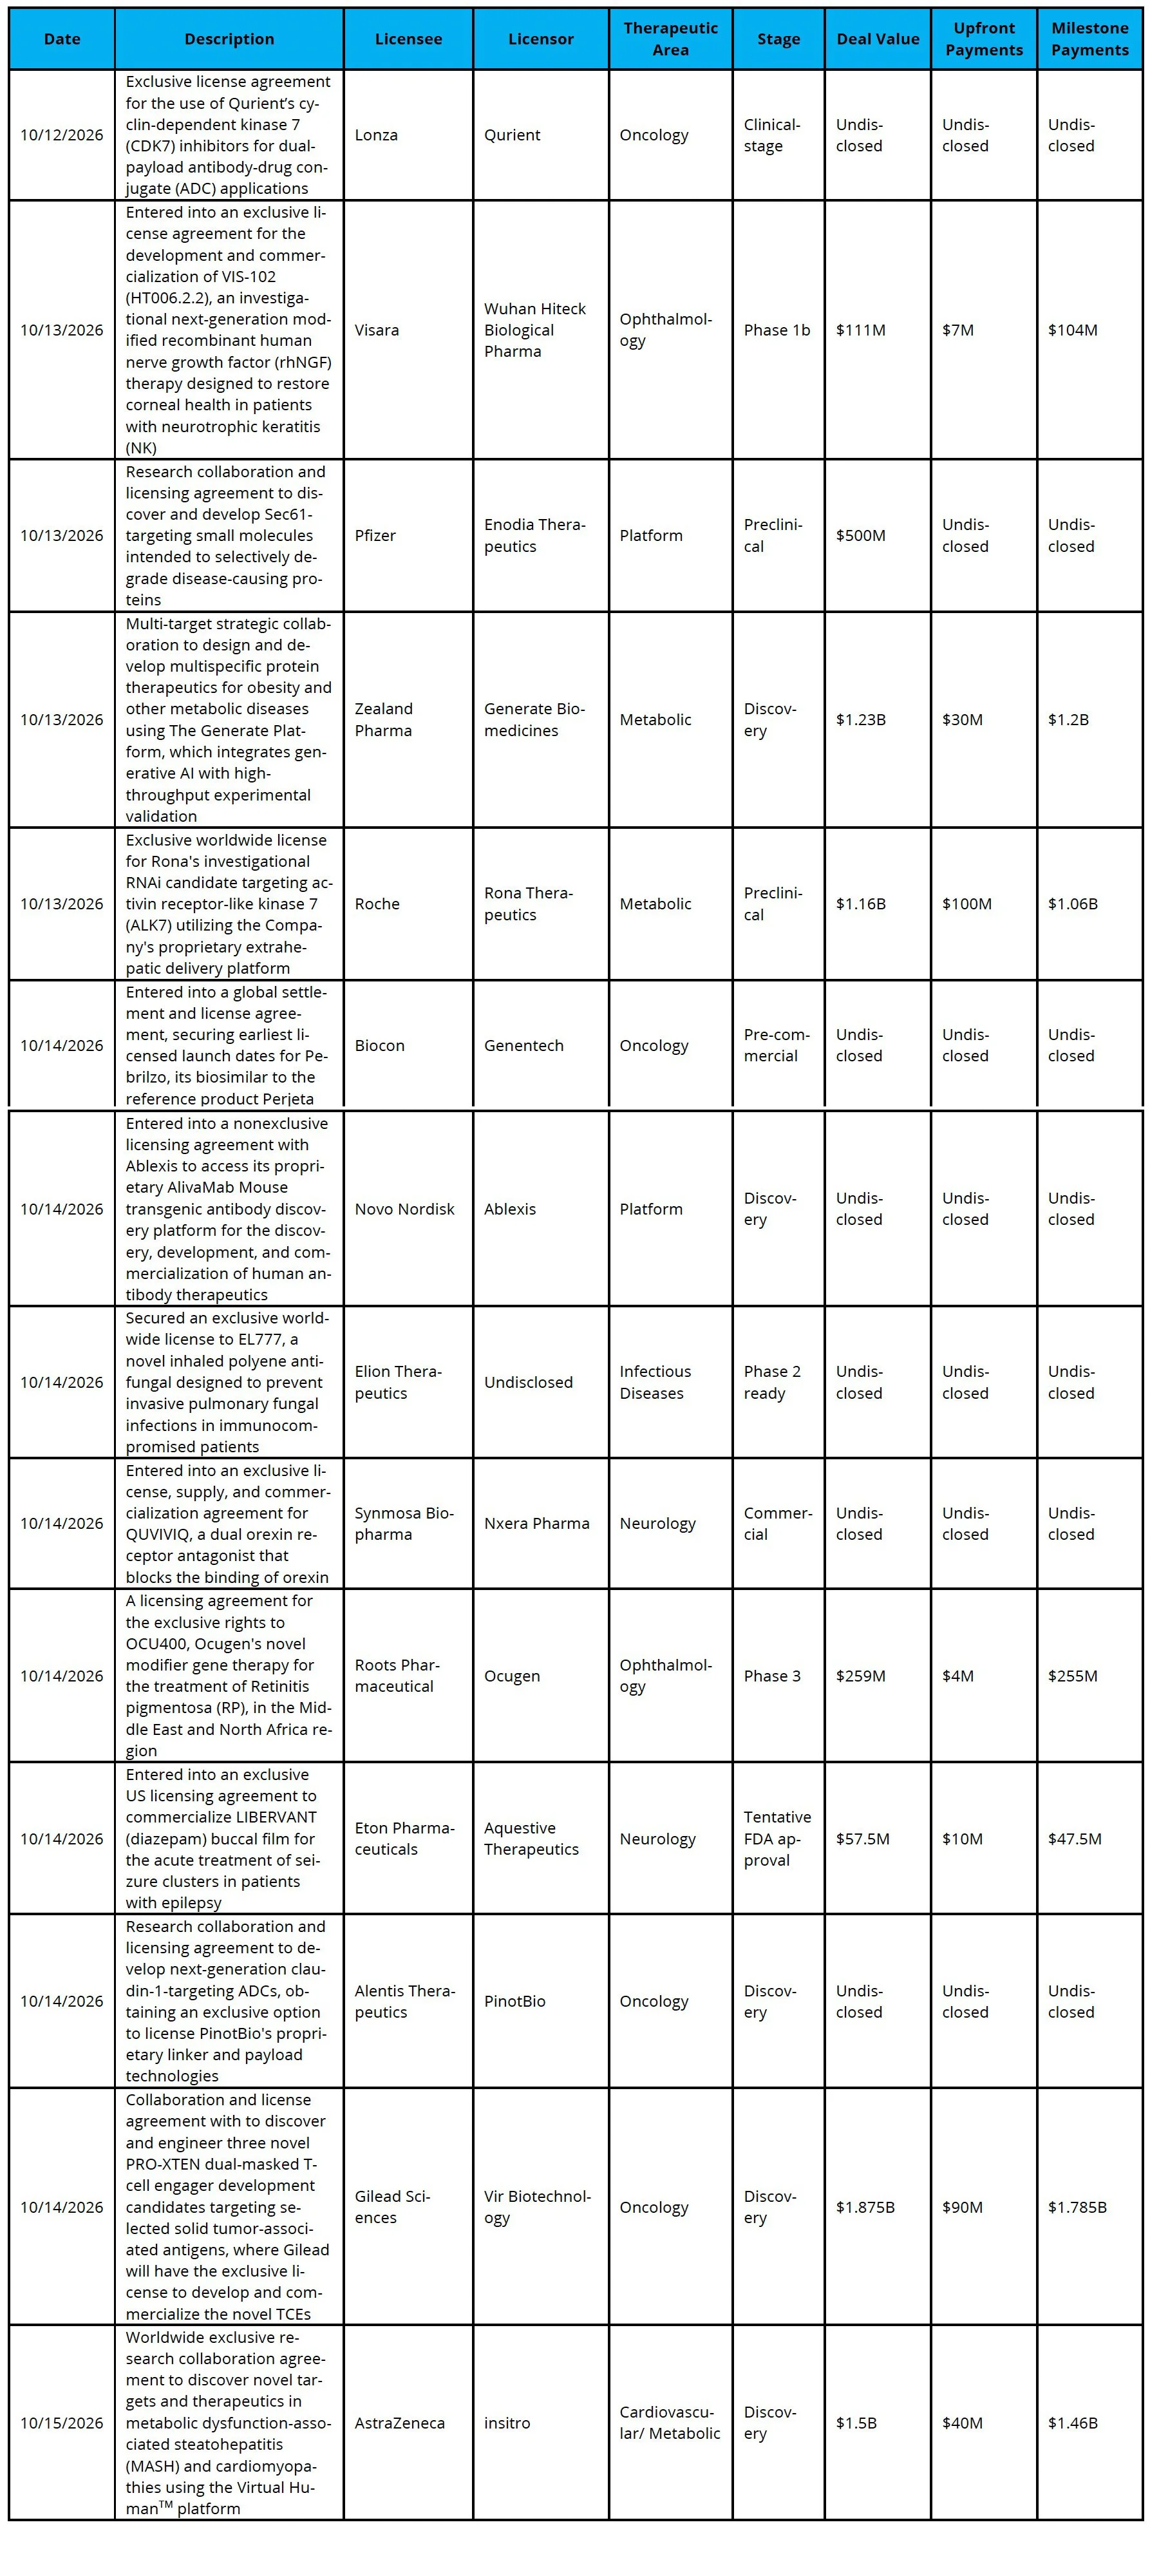
Licensing
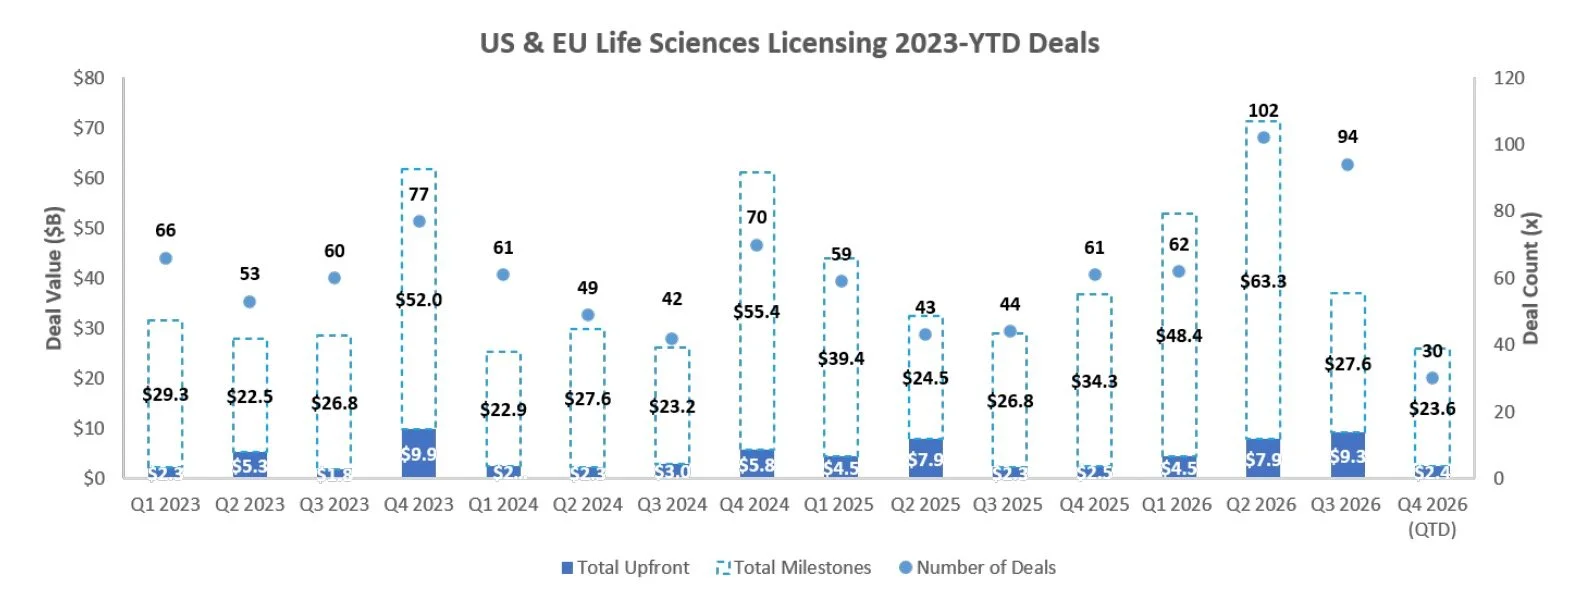
Fourteen licensing agreements were recorded, led by Gilead/Vir, AstraZeneca/insitro, Zealand/Generate, and Roche/Rona. The terms favor staged commitments; upfront payments were modest relative to headline values, leaving most consideration dependent on progress. Oncology, metabolic disease, and discovery technologies remained the principal areas of interest.
Sources: Pitchbook, Biomedtracker, and CapIQ
Sources: Pitchbook, Biomedtracker, and CapIQ
M&A
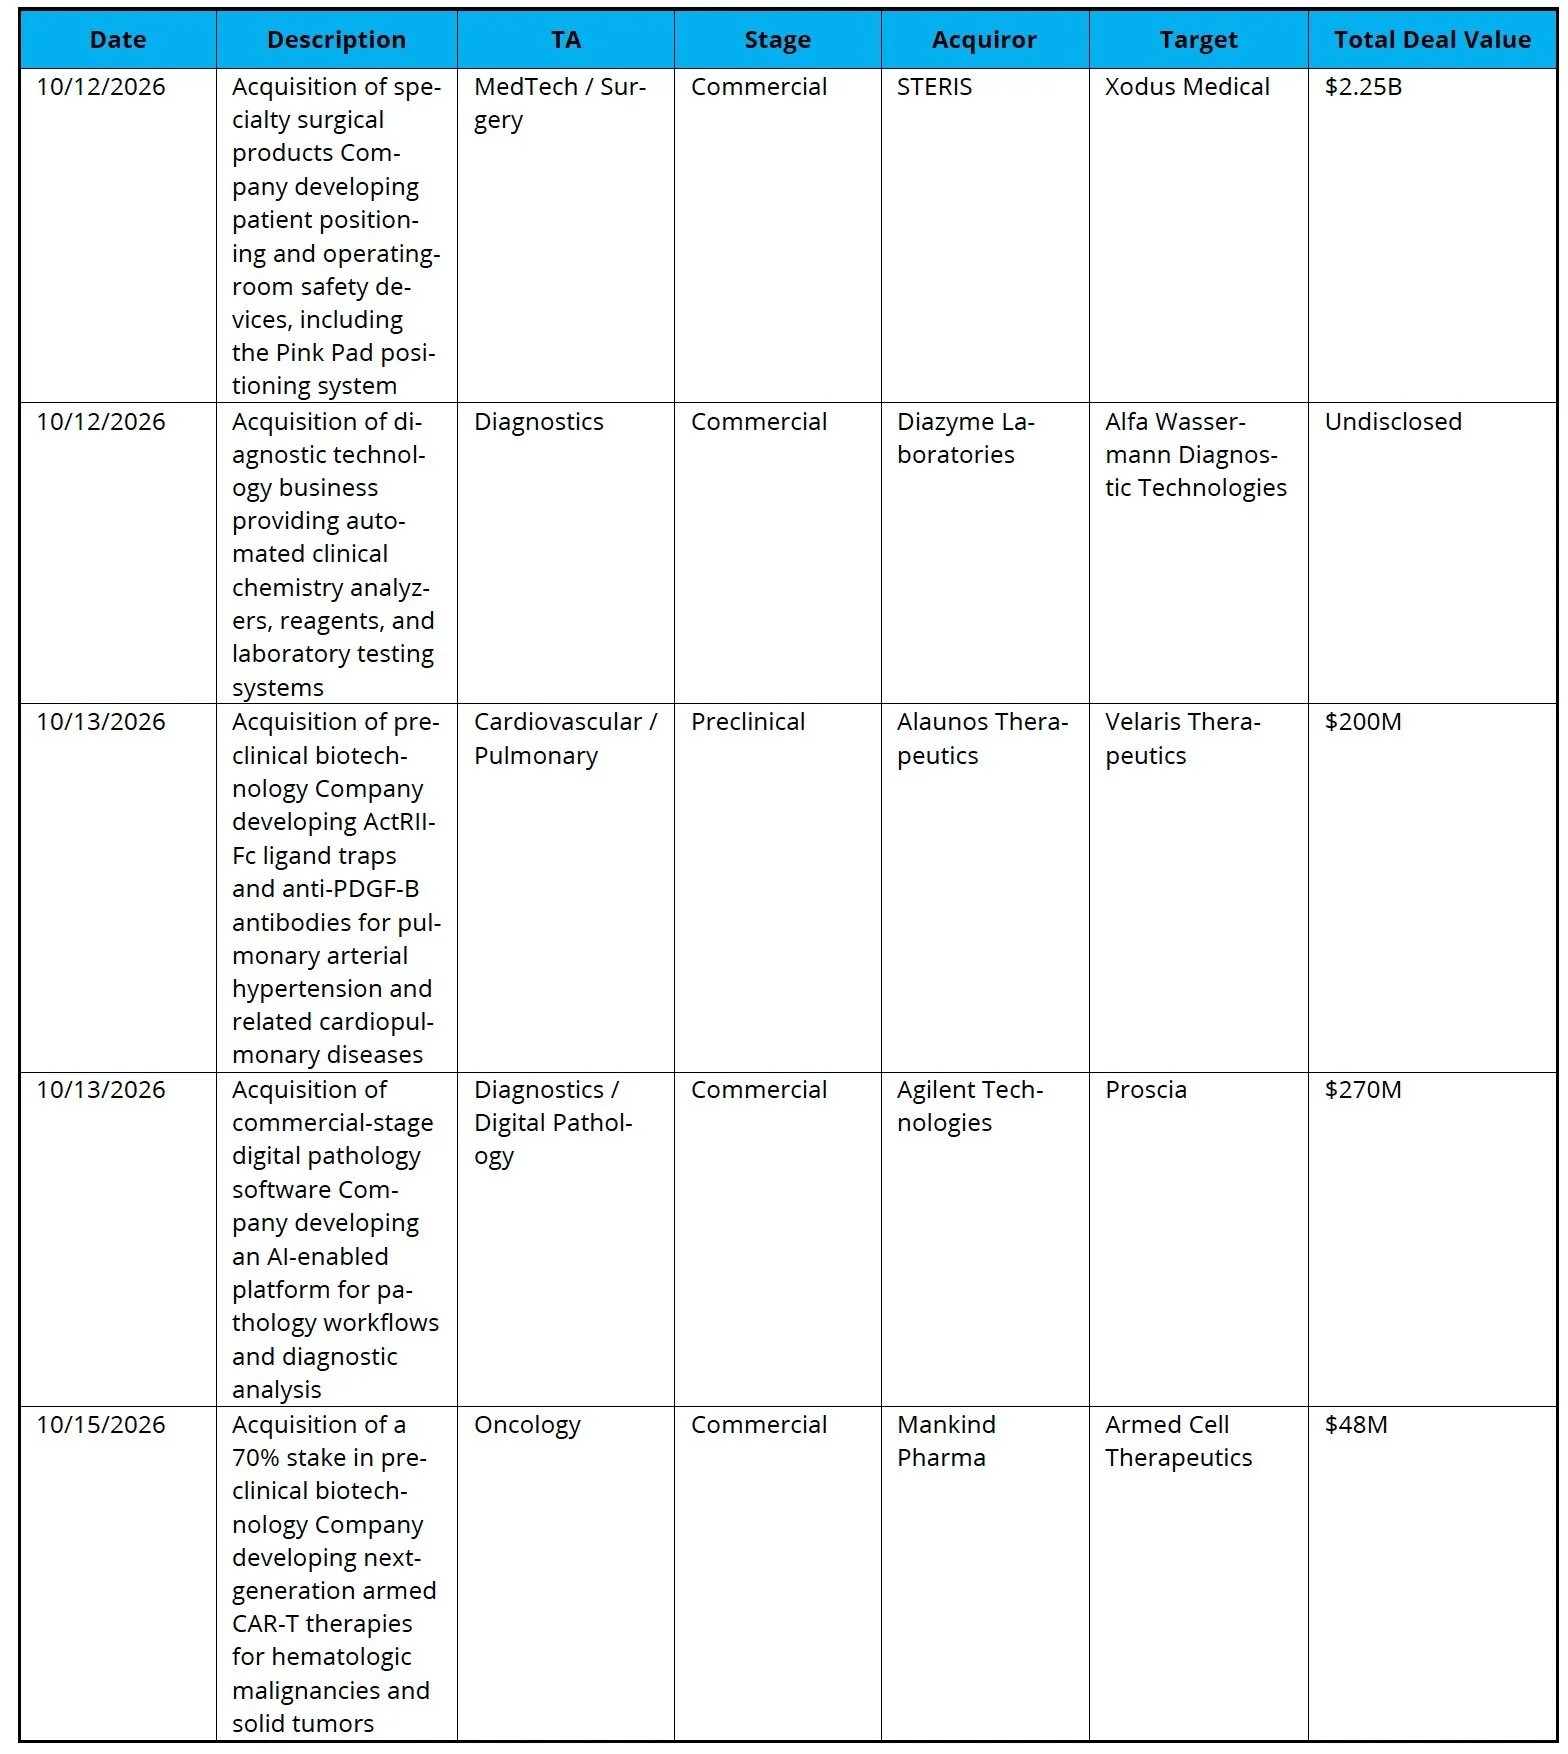
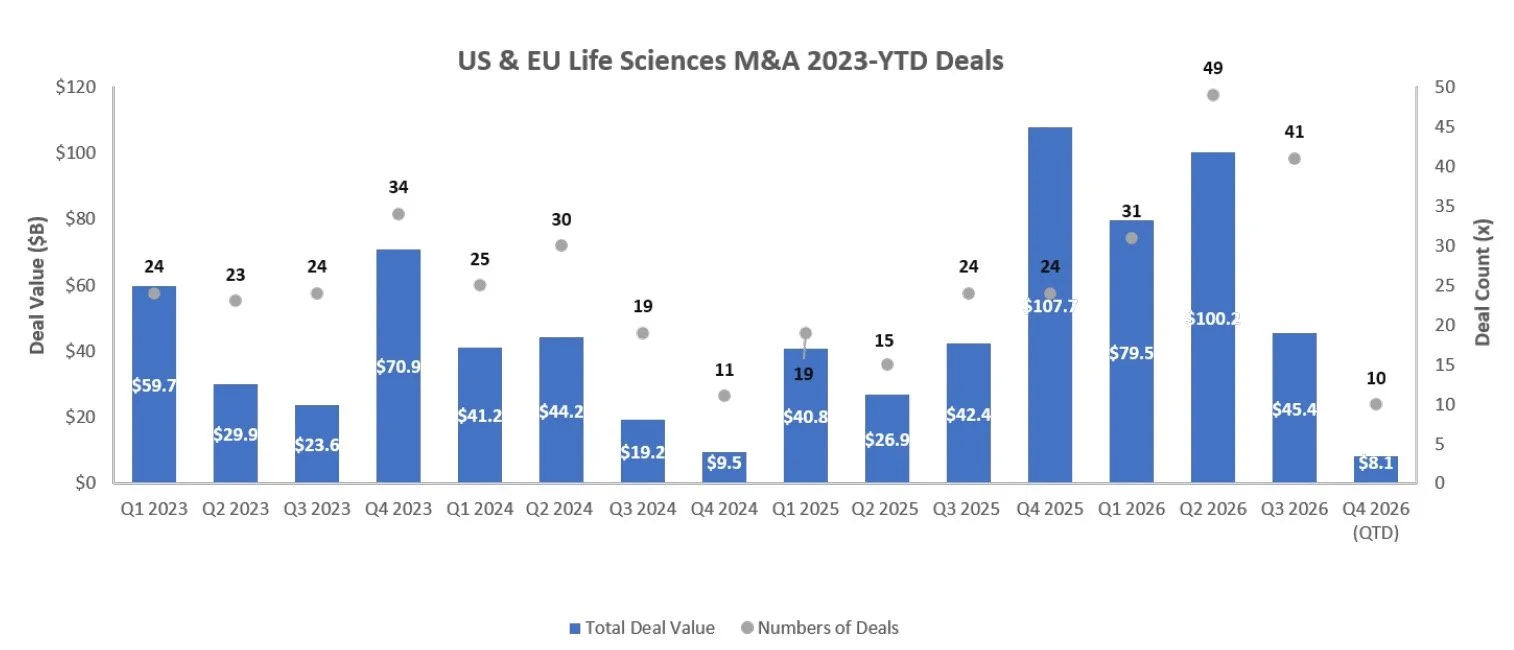
STERIS/Xodus and Agilent/Proscia illustrate two routes to strategic value: extending an operating-room product franchise and embedding software in a diagnostics workflow. Alaunos/Velaris, by contrast, combined an asset acquisition with a concurrent financing. The structures differ, but each transaction has a specific operating or development rationale.
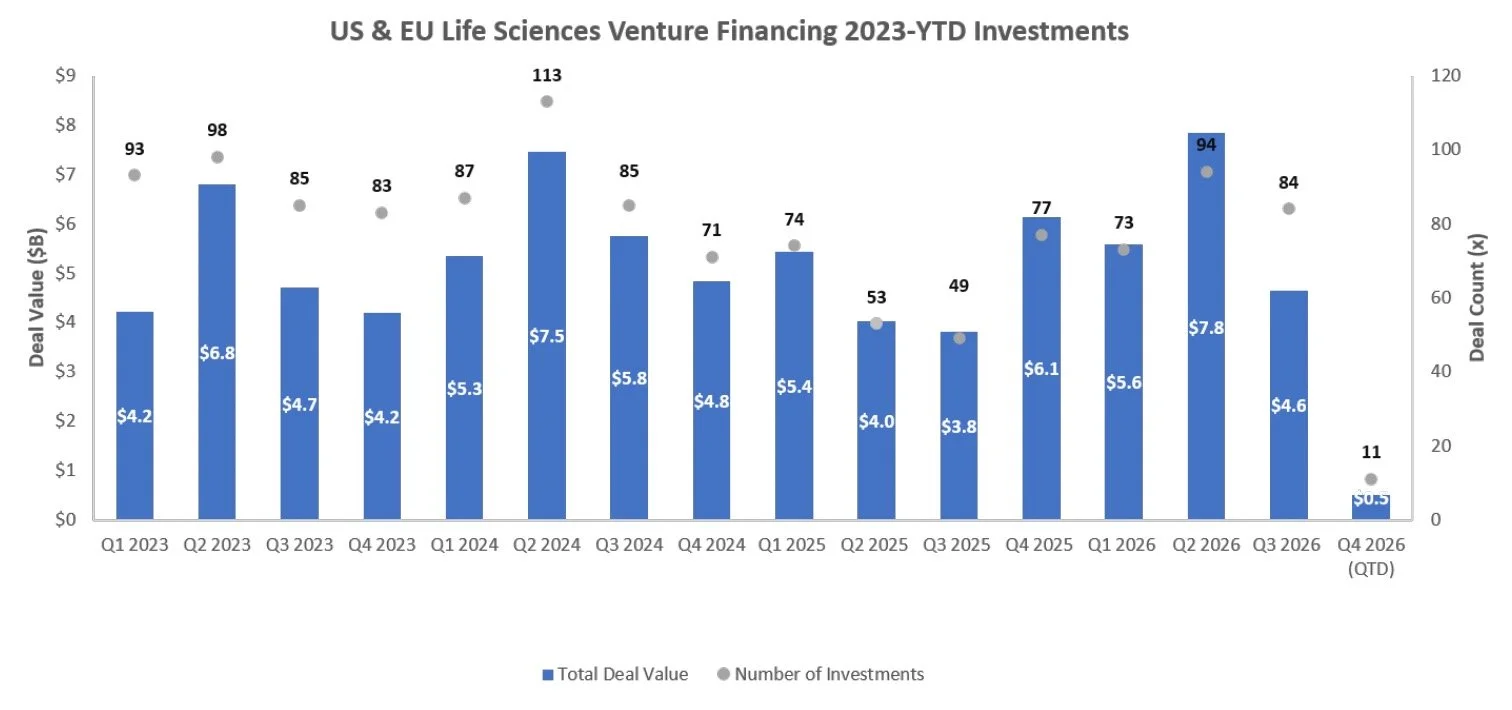
Venture Financing
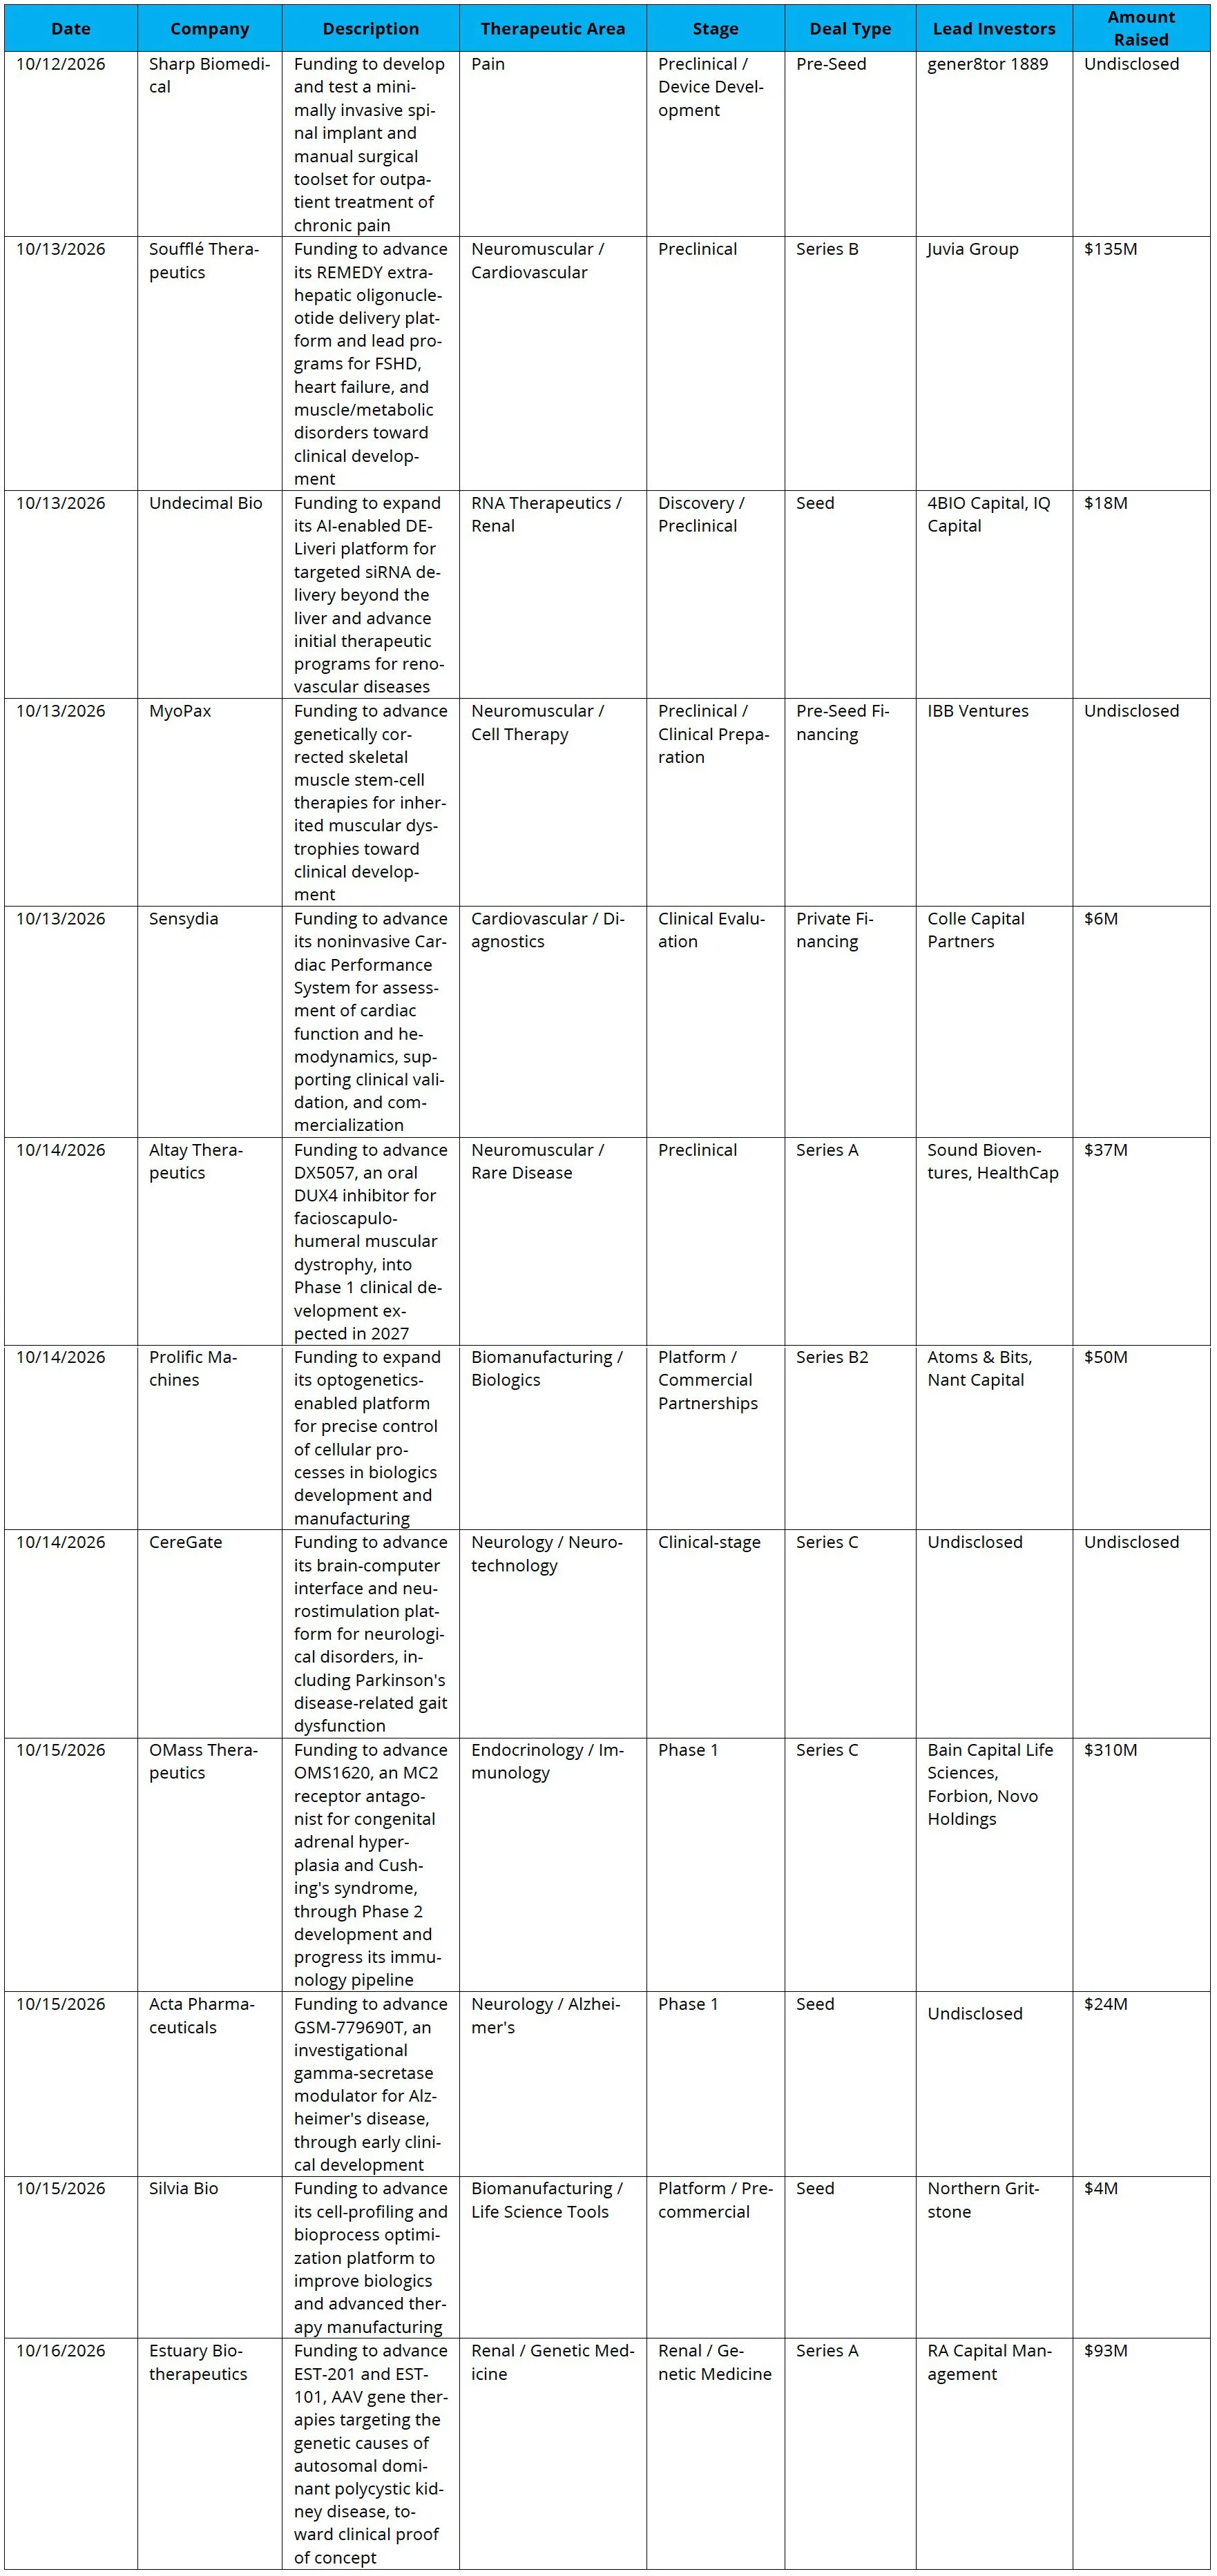
OMass ($310M), Soufflé ($135M), and Estuary ($93M) led a week of sizeable specialist rounds. The financings span clinical drug development, oligonucleotide delivery, and renal gene therapy. Investors continued to underwrite distinct technical risks rather than a single sector theme.
The Case for a New Generation of Oral Therapies in Inflammatory Bowel Disease
Back Bay Life Science Advisors and Nimbus Therapeutics
Despite advances in the treatment of inflammatory bowel disease (IBD), many patients with moderate-to-severe ulcerative colitis (UC) and Crohn’s disease continue to experience inadequate disease control with available biologics and targeted therapies.
HEALTHCARE MARKET REPORTS ARCHIVE
-
-
-
-
-
-
-
April 17, 2026
April 24, 2026 -
-
-
-
-
-
-
-
-
-
-
-
-
-
-
About DNB Carnegie Back Bay
DNB Carnegie Back Bay drives global healthcare growth and innovation by providing a full range of strategic advisory and financing capabilities along the continuum of life science and healthcare company development. The DNB Carnegie Back Bay Healthcare Partnership is a marketing term referring to a strategic agreement between DNB Markets, Inc. and Back Bay Life Science Advisors. More information about the DNB Carnegie Back Bay Healthcare Partnership can be found here.
Securities products and services are offered in the US through DNB Carnegie, Inc., a US-registered broker-dealer and a separately incorporated subsidiary of DNB Bank ASA. DNB Carnegie, Inc. is a member of the Financial Industry Regulatory Authority (“FINRA”) and the Securities Investor Protection Corporation (“SIPC”). Securities products and services are offered in the European Economic Area through DNB Carnegie.