

Week of September 25, 2026
The Week at a Glance:
Healthcare capital markets remained constructive despite a less supportive macro backdrop, with continued IPO issuance, large-scale platform licensing and strategic M&A demonstrating sustained capital availability for differentiated assets. Activity remains highly selective: investors are focused on clinically validated assets and clear development plans, while strategic buyers continue to prioritize platform optionality, differentiated modalities and scarce capabilities. Overall, the market has continued to normalize, but remains disciplined, with high-quality assets able to attract meaningful capital and strategic interest.
Rates Rise, Risk Appetite Holds: Equities advanced despite 10-year yields above 5%.
Biotech IPOs Stay Open: ADARx raised $446M; Iambic and City filed S-1s.
Platform BD Remains Strong: Lilly, Roche / Genentech and Novo signed multi-billion-dollar deals.
Markets Overview
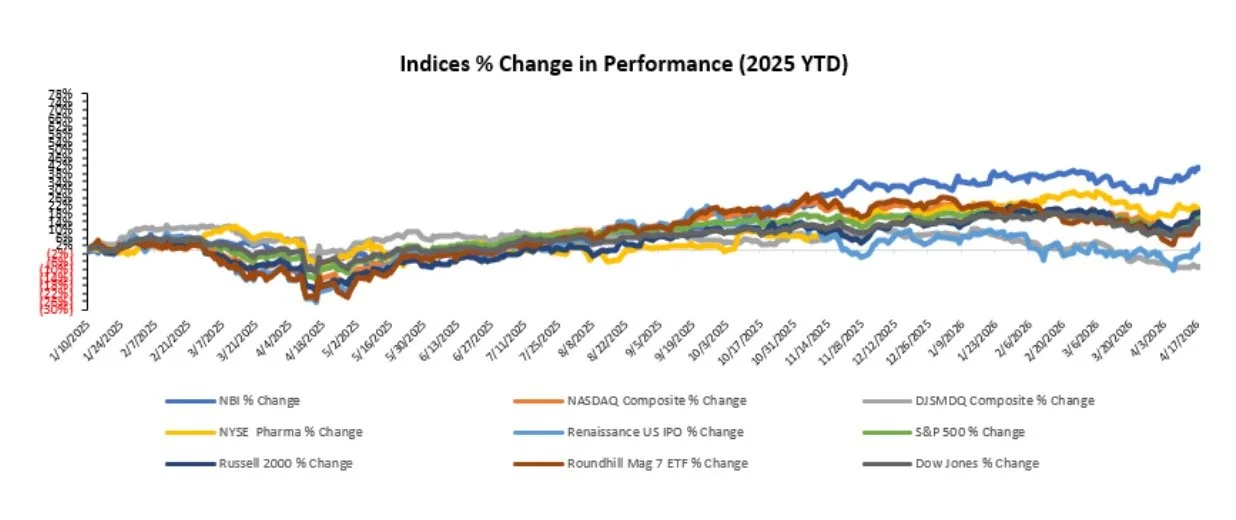
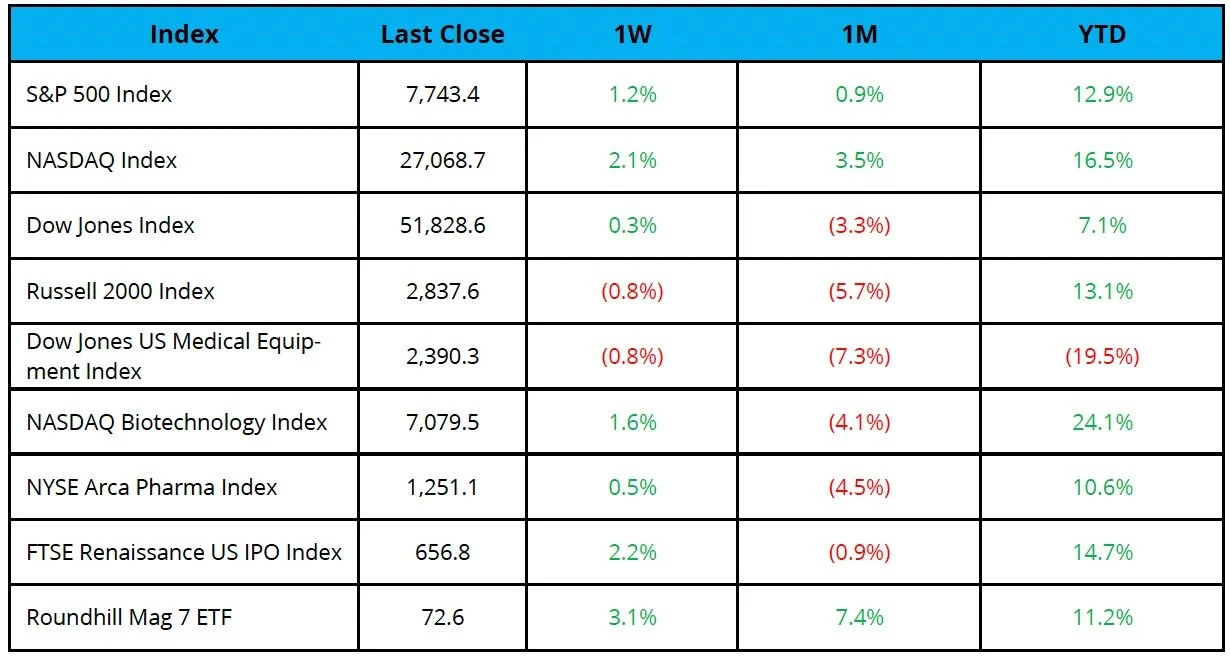
The Nasdaq was up 2.1%, and the S&P 500 and Dow were up 1.2% and 0.3%, respectively, over the last week
Higher yields did not derail risk appetite: large-cap growth led, biotech gained 1.6%, and small caps lagged. The divergence suggests investors are still funding differentiated growth, but remain selective on duration and quality.
The NYSE Pharma Index and NBI were up 0.5% and 1.6%, respectively, over the last week
Notable change in share price:
Surrozen (NASDAQ: SRZN): Shares rose 108.4% after Merck reported positive Phase 2b/3 data for trispecific Wnt agonist Remigromig in DME, validating the Wnt pathway but showing higher rates of proliferative diabetic retinopathy and vitreous hemorrhage, which highlighted the potential benefit of Surrozen’s SZN-8141 combining Wnt agonism with VEGF inhibition
GRAIL (NASDAQ: GRAL): Shares rose ~55% through September 24 after FDA briefing documents raised no major concerns regarding the safety or accuracy of GRAIL’s Galleri multi-cancer early detection (MCED) test and an FDA advisory committee recommended approval of the Premarket Approval (PMA) application
Viking Therapeutics (NASDAQ: VKTX): Shares rose 35.7% after the Company reported positive maintenance data for VK2735, its dual GLP-1/GIP receptor agonist, showing superior weight maintenance following transition to either every other week or monthly dosing compared to those transitioning to placebo
Sources: Pitchbook, Biomedtracker, and CapIQ
Equity Markets
IPO
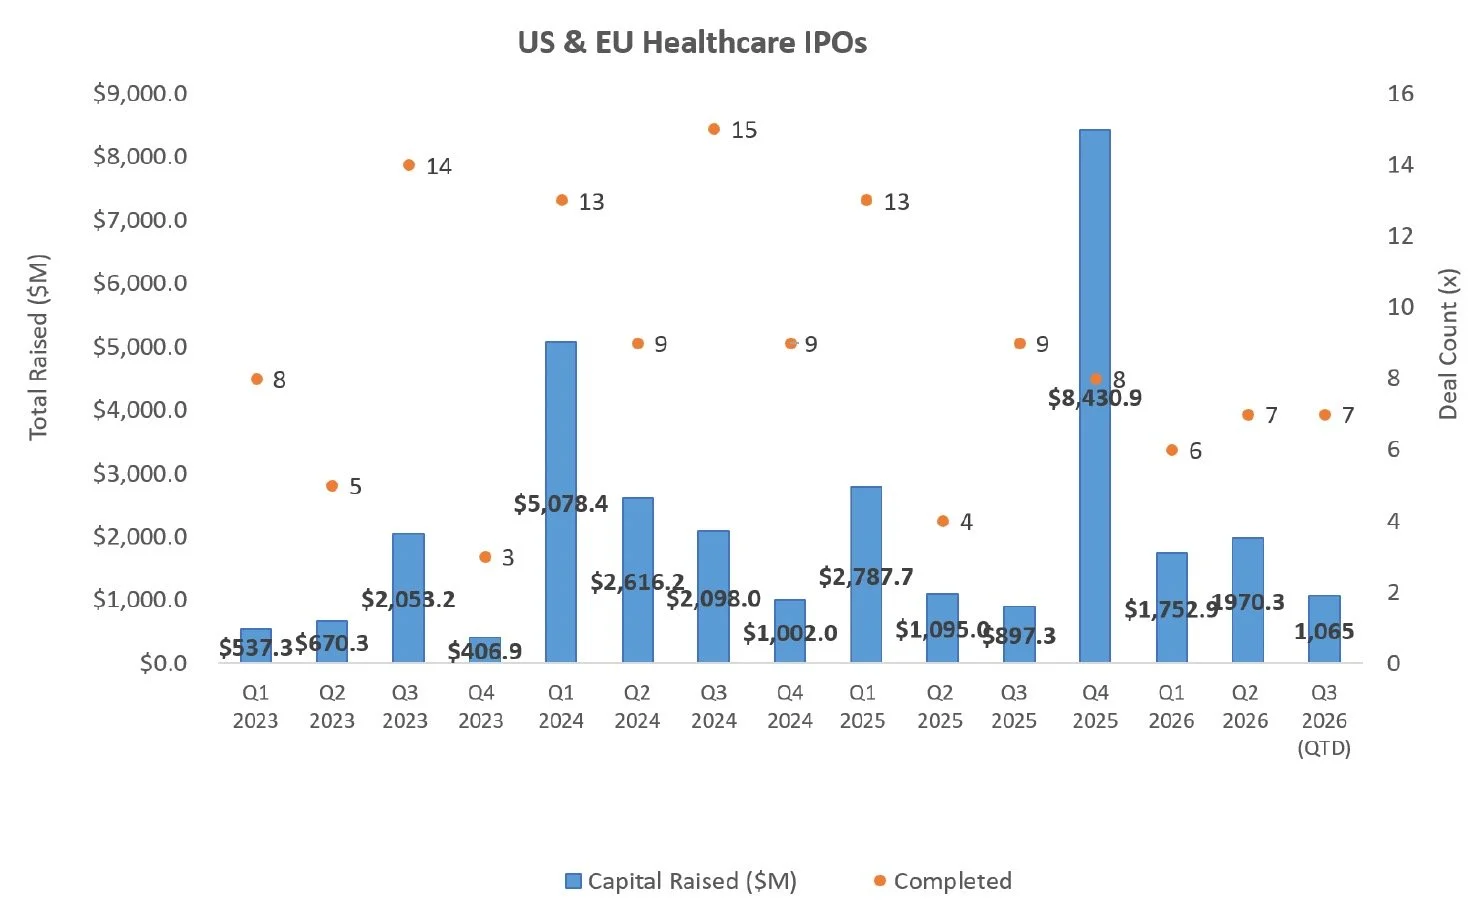
The IPO window continued to broaden, with ADARx pricing a $446.3M offering and Iambic and City Therapeutics filing to follow. However, the market remains highly selective, with clinical-stage IPOs still generating negative median aftermarket returns, suggesting access to the public markets is improving faster than overall performance.
One biotech IPO priced last week and two filed their S-1s:
ADARx Pharmaceuticals raised $446.3M in its IPO to advance agazisiran through Phase 2 and potential Phase 3 development across complement-mediated diseases, complete the Phase 3 STOP-HAE trial for onvuzosiran and support pre-commercial activities, while advancing ADX-626, ADX-077, and ADX-199 through early clinical development
Iambic Therapeutics filed to raise up to ~$100.0M in an IPO to advance its lead HER2 inhibitor IAM1363, including toward potential registrational development, while advancing KIF18A inhibitor IAM217 and dual CDK2/4 inhibitor IAM-C1 into Phase 1/2 development and supporting working capital and general corporate purposes
City Therapeutics filed to raise up to ~$100.0M in an IPO to advance CITY-FXI through Phase 1 and initiate a Phase 2 trial in total knee arthroplasty, advance CITY-RBP4 into Phase 1 development for Stargardt disease and geographic atrophy, and progress CITY-TFR2 through early clinical development in anemia of chronic disease, while supporting its RNAi platform and discovery programs
IPOs priced in 2025 and 2026 have generated a median and average return of 13.6% and 30.2% YTD, respectively
After-Market Performance by Stage:
Clinical-stage after-market performance: 28.2% (average), (6.4%) (median)
Commercial-stage after-market performance: 32.2% (average), 23.1% (median)
After-Market Performance by Sector:
Biopharma: 28.2% (average), (6.4%) (median)
MedTech: 29.3% (average), 17.6% (median)
Source: CapIQ
Follow On
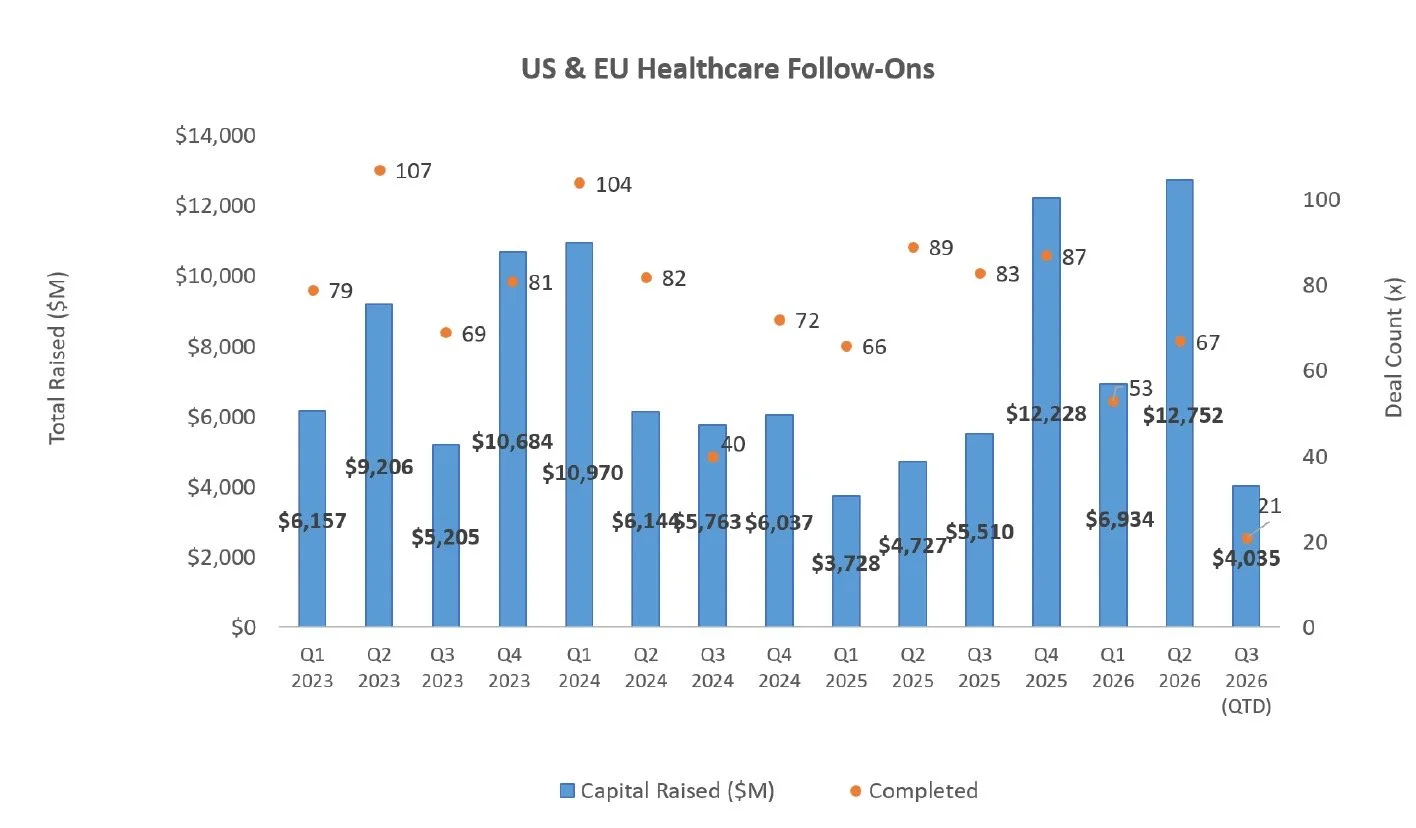
Positive clinical catalysts are translating quickly into financing opportunities, with Viking raising $500.0M across concurrent equity and convertible offerings following positive VK2735 data.
There was one follow-on offering last week totaling $275.0M:
Viking Therapeutics (NASDAQ: VKTX) priced a $275.0M public offering, consisting of 7.9M shares at $35.00 per share, to fund the continued clinical development, advancement and commercialization of VK2735 in obesity, continued development of VK3019, and other R&D, working capital and general corporate purposes; Viking concurrently raised $225.0M through convertible senior notes, bringing the combined financing to $500.0M
Source: Biomedtracker
PIPE/RDO
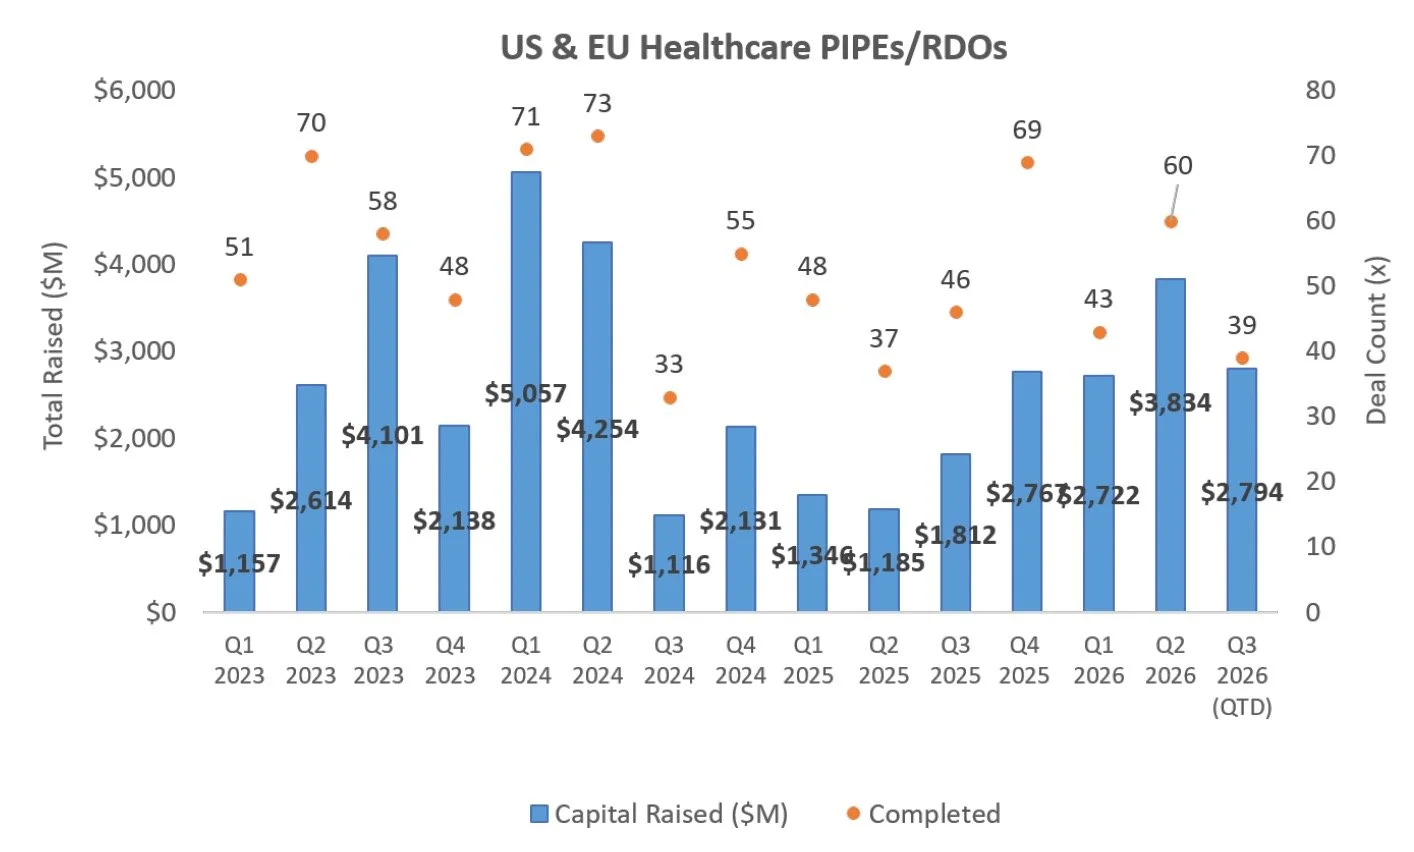
PIPE / RDO activity was light this week, with just $11.5M raised across two transactions. Public capital formation was therefore concentrated in conventional IPO and follow-on channels rather than structured financing.
Licensing
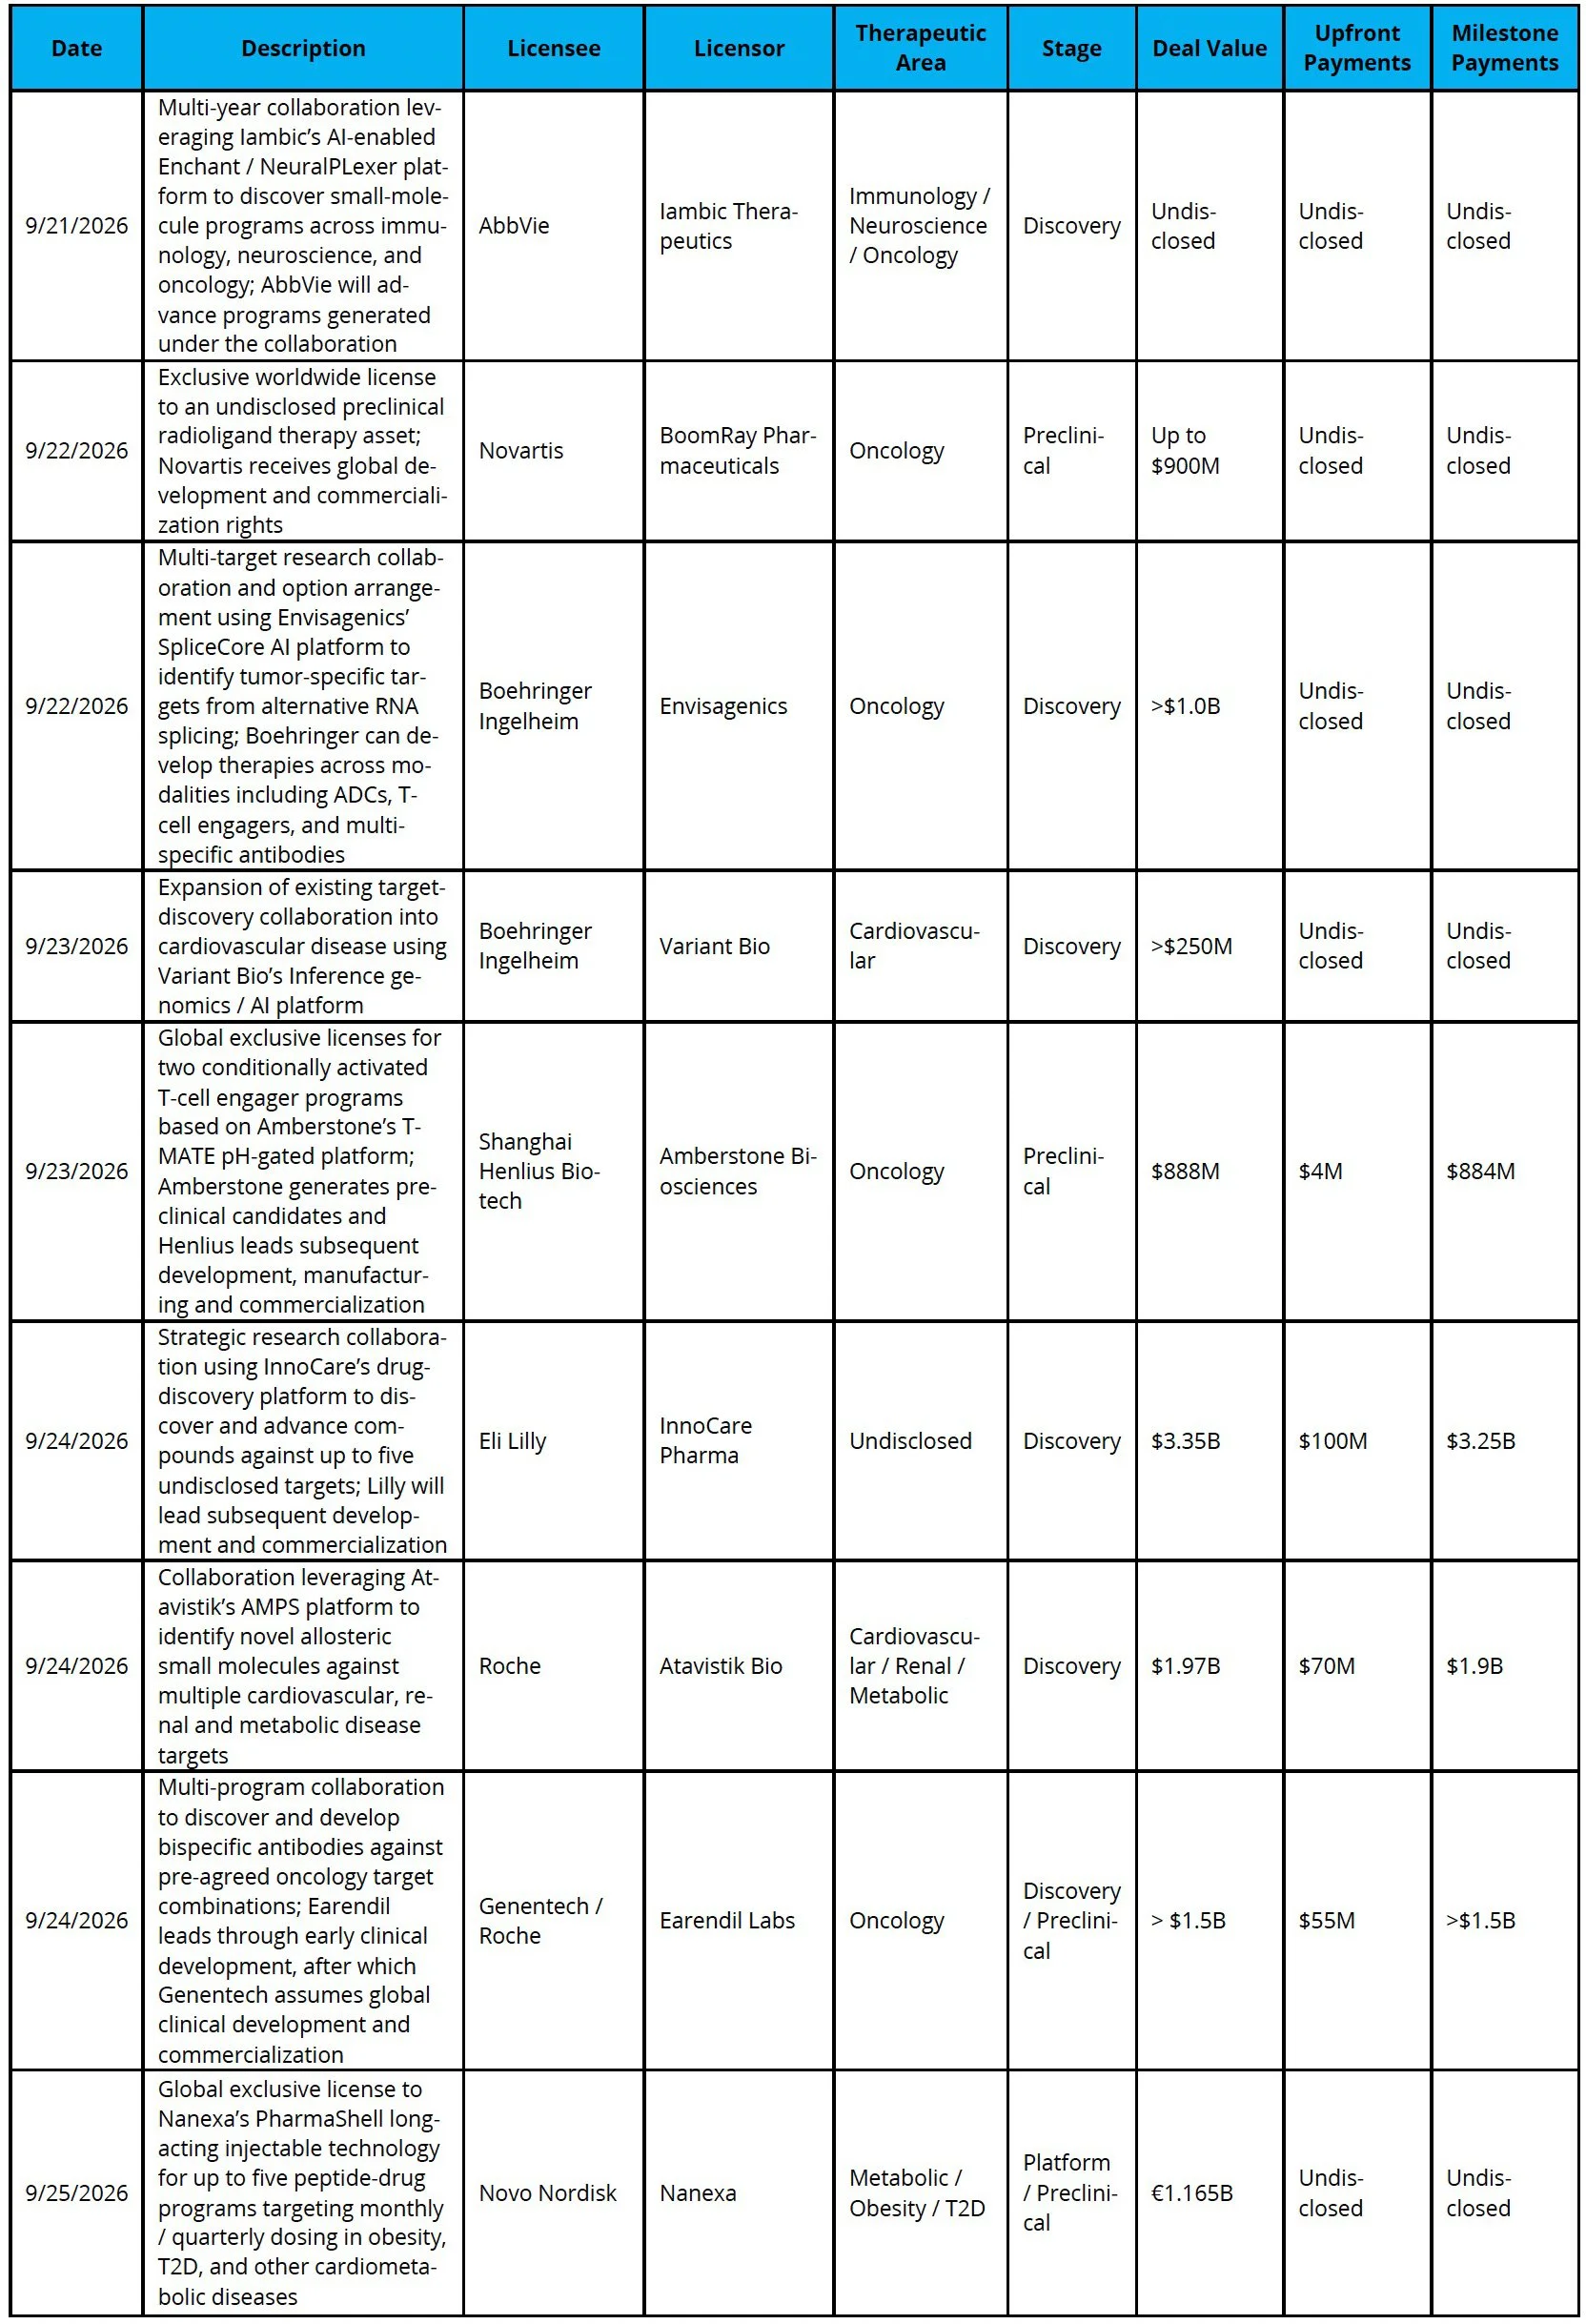
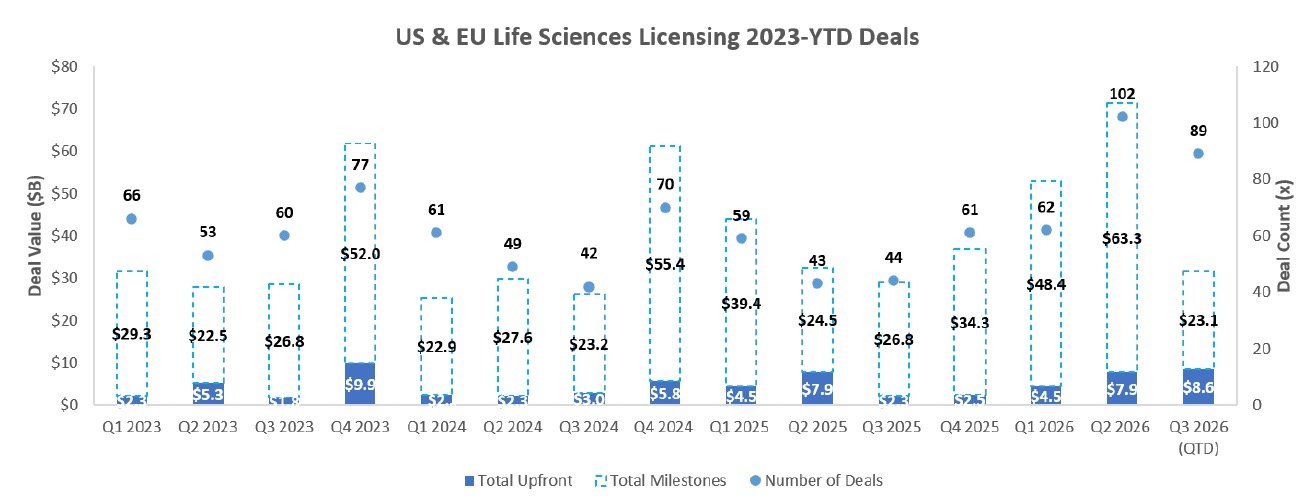
Platform transactions again drove strategic BD, with large headline values across AI-enabled discovery, multispecifics, radioligands and cardiometabolic technologies. Milestone-heavy structures allow pharma to retain multi-program optionality while limiting upfront capital deployment ahead of technical validation.
Sources: Pitchbook, Biomedtracker, and CapIQ
Sources: Pitchbook, Biomedtracker, and CapIQ
M&A
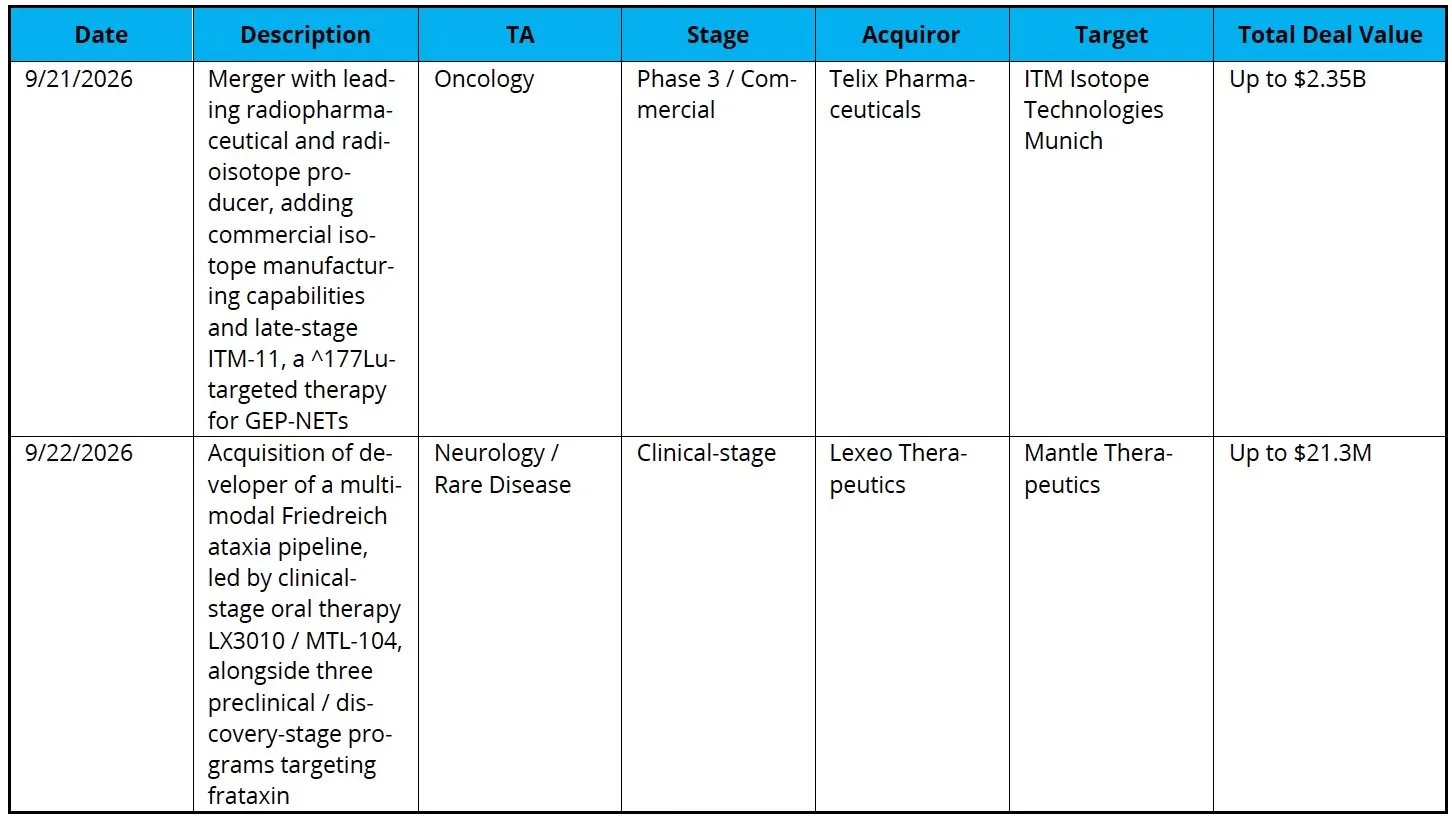
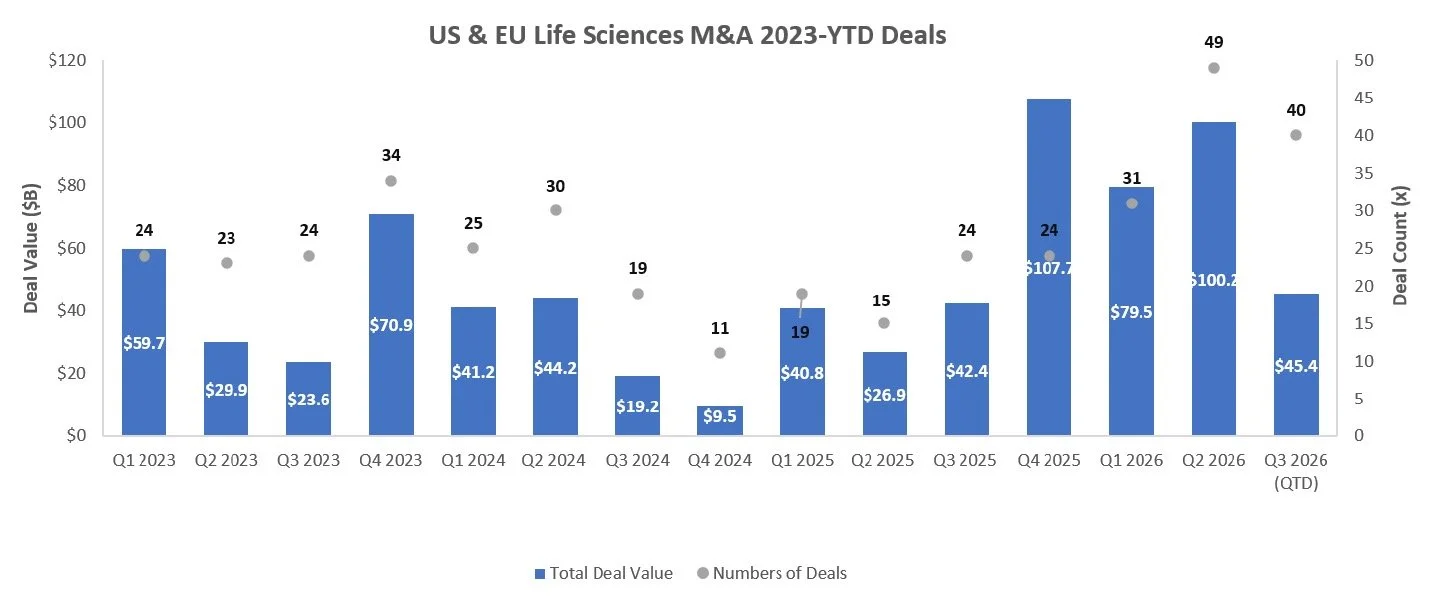
M&A was concentrated, but strategically meaningful: Telix / ITM accounted for nearly all announced value and extends radiopharma consolidation upstream into isotope supply. Control of manufacturing infrastructure is becoming part of competitive advantage as the modality scales.
Venture Financing
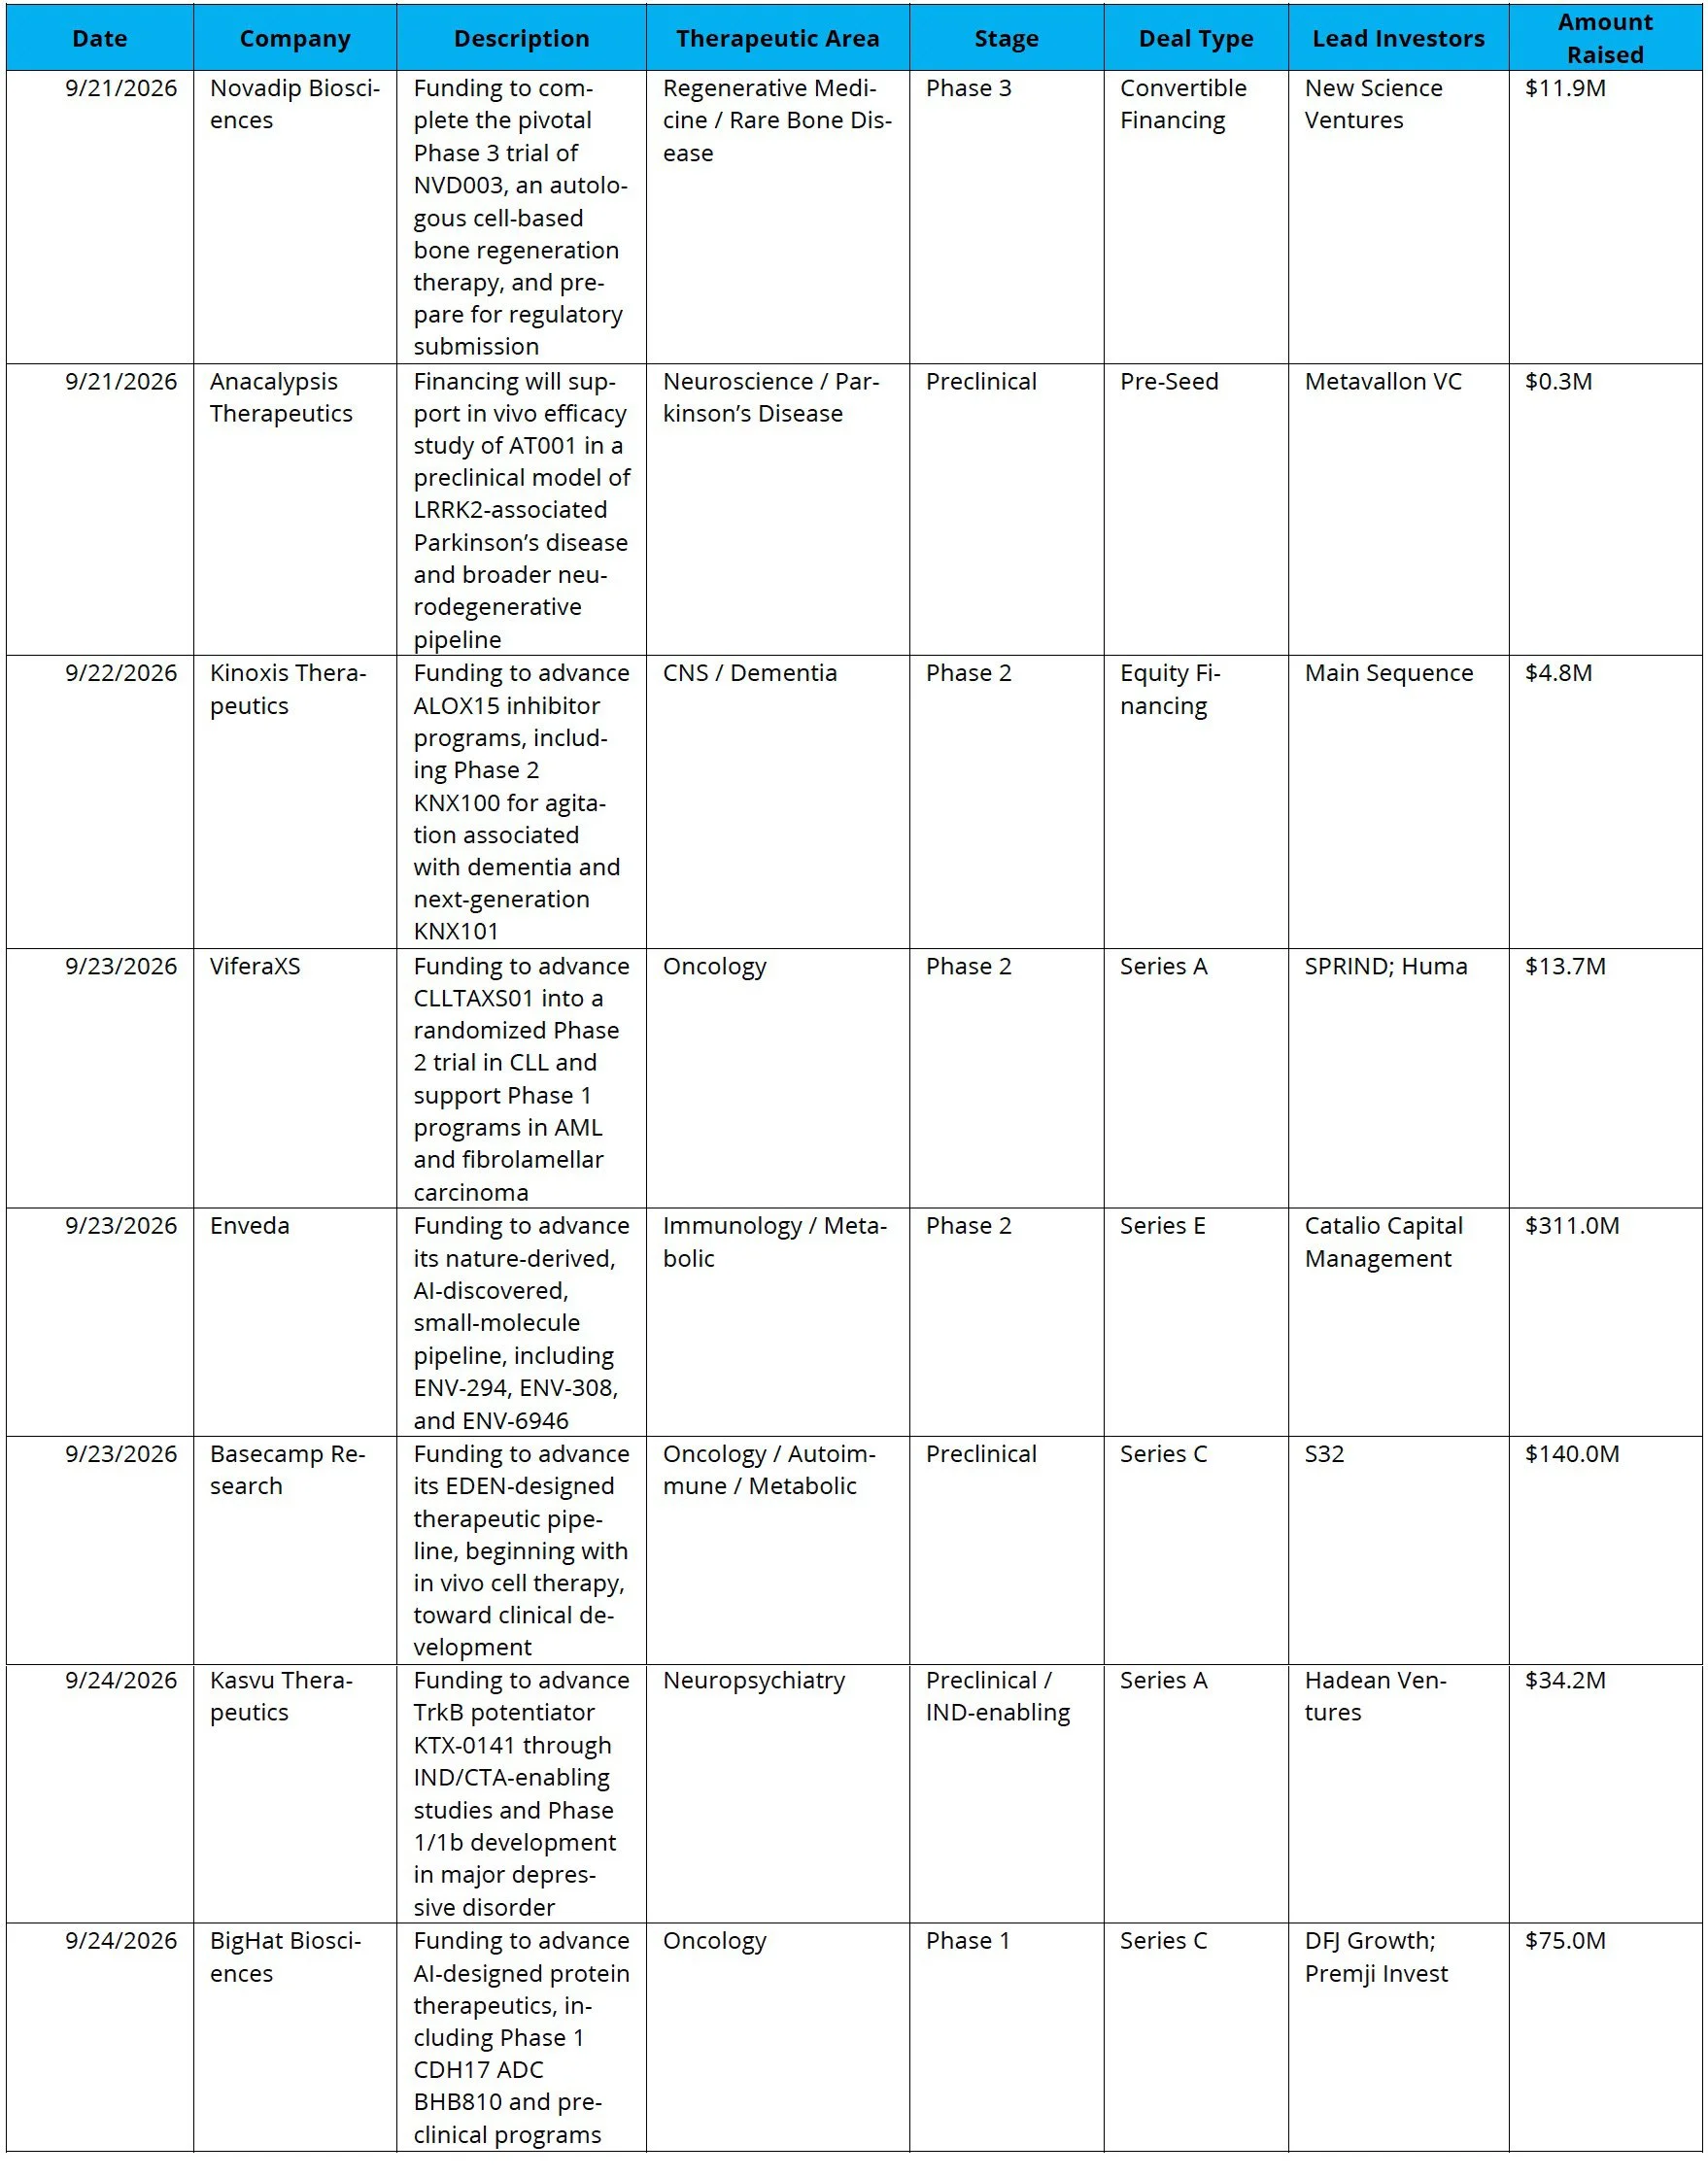
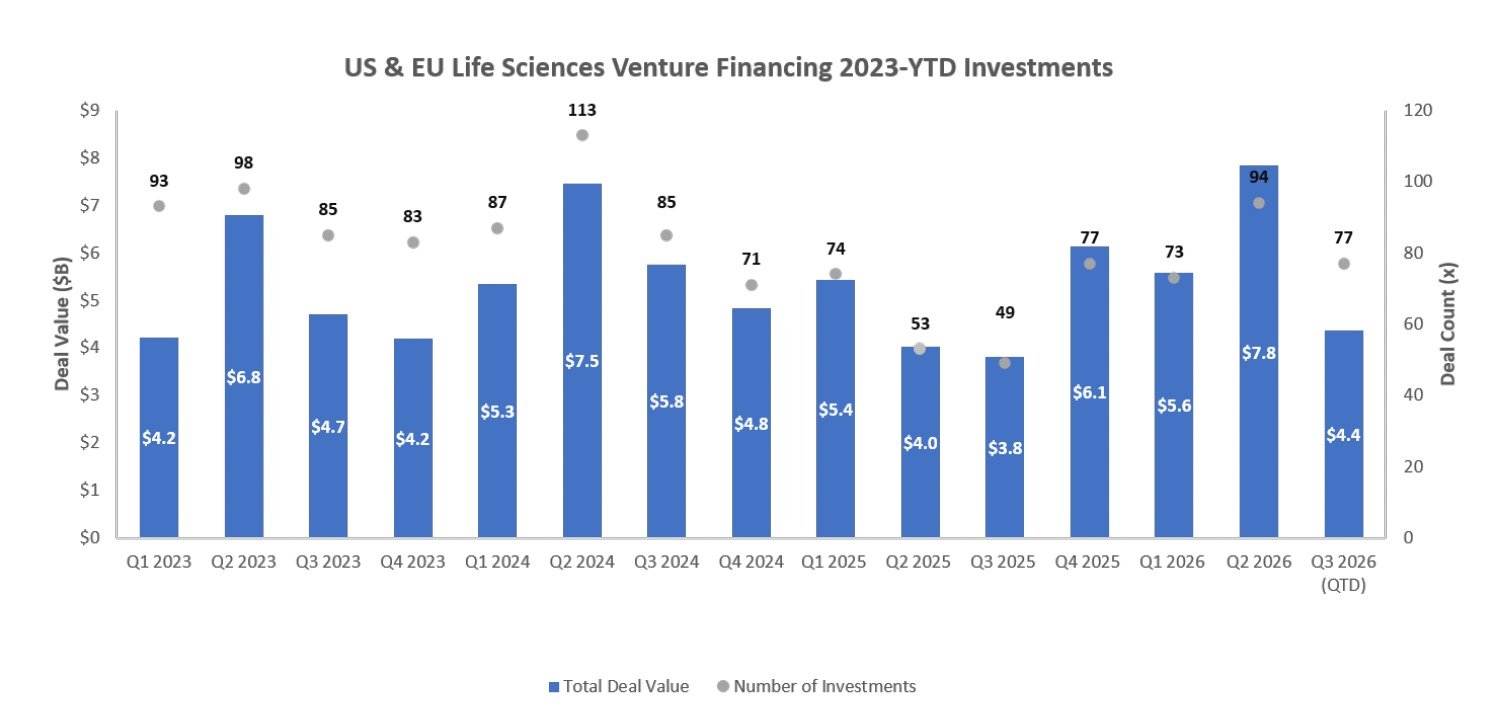
Venture deployment remained selective but capable of supporting very large rounds, particularly for differentiated discovery platforms with advancing pipelines. Enveda and Basecamp illustrate continued concentration of capital around AI-enabled platforms with multiple shots on goal.
The Case for a New Generation of Oral Therapies in Inflammatory Bowel Disease
Back Bay Life Science Advisors and Nimbus Therapeutics
Despite advances in the treatment of inflammatory bowel disease (IBD), many patients with moderate-to-severe ulcerative colitis (UC) and Crohn’s disease continue to experience inadequate disease control with available biologics and targeted therapies.
HEALTHCARE MARKET REPORTS ARCHIVE
-
-
-
-
-
-
April 17, 2026
April 24, 2026 -
-
-
-
-
-
-
-
-
-
-
-
-
-
-
About DNB Carnegie Back Bay
DNB Carnegie Back Bay drives global healthcare growth and innovation by providing a full range of strategic advisory and financing capabilities along the continuum of life science and healthcare company development. The DNB Carnegie Back Bay Healthcare Partnership is a marketing term referring to a strategic agreement between DNB Markets, Inc. and Back Bay Life Science Advisors. More information about the DNB Carnegie Back Bay Healthcare Partnership can be found here.
Securities products and services are offered in the US through DNB Carnegie, Inc., a US-registered broker-dealer and a separately incorporated subsidiary of DNB Bank ASA. DNB Carnegie, Inc. is a member of the Financial Industry Regulatory Authority (“FINRA”) and the Securities Investor Protection Corporation (“SIPC”). Securities products and services are offered in the European Economic Area through DNB Carnegie.