

Week of October 9, 2026
The Week at a Glance:
Healthcare capital markets improved during the week, led by a return of biotech IPO issuance and nearly $900M in follow-on equity. Three acquisitions totaling approximately $4.6B underscored continued demand for commercial assets and specialized infrastructure. Licensing remained active, though with smaller upfront commitments than the prior week. Investors continued to distinguish sharply among clinical outcomes: Vaxcyte gained 30.7% on Phase 3 data, while ArriVent fell 47.0% after a failed pivotal trial.
Public financing broadened: Two IPOs raised $161.7M, following no pricings the prior week; four follow-ons raised $872.5M, up from $357M. Vaxcyte separately placed $500M in convertible notes.
Strategic M&A returned to the foreground: Shionogi/IntraBio ($2B), Viatris/Pacira ($1.65B), and GE HealthCare/SOFIE ($945M) combined commercial products with targeted pipeline and operating capabilities.
Licensing favored targeted assets and rights: CSL/Alentis ($355M upfront) and Genentech/Alector ($100M upfront) led disclosed payments, while other agreements focused on regional commercialization, formulation, and discovery platforms.
Markets Overview
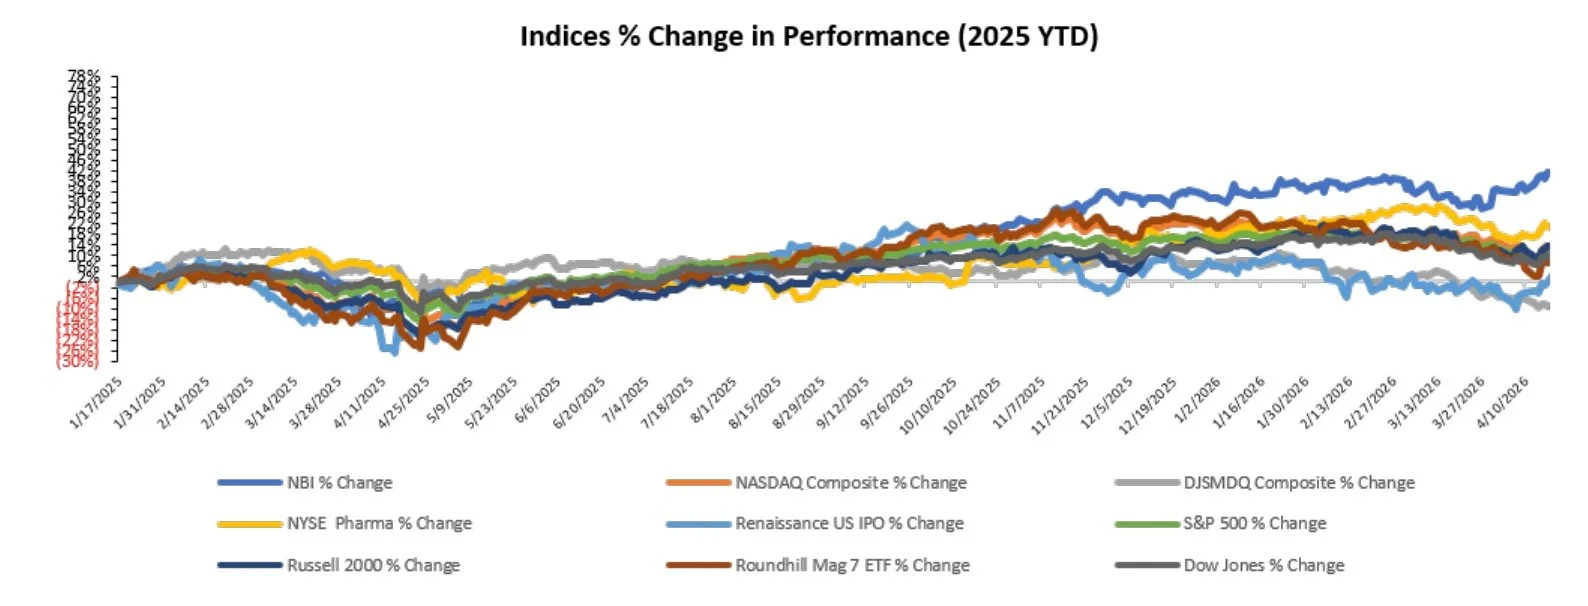
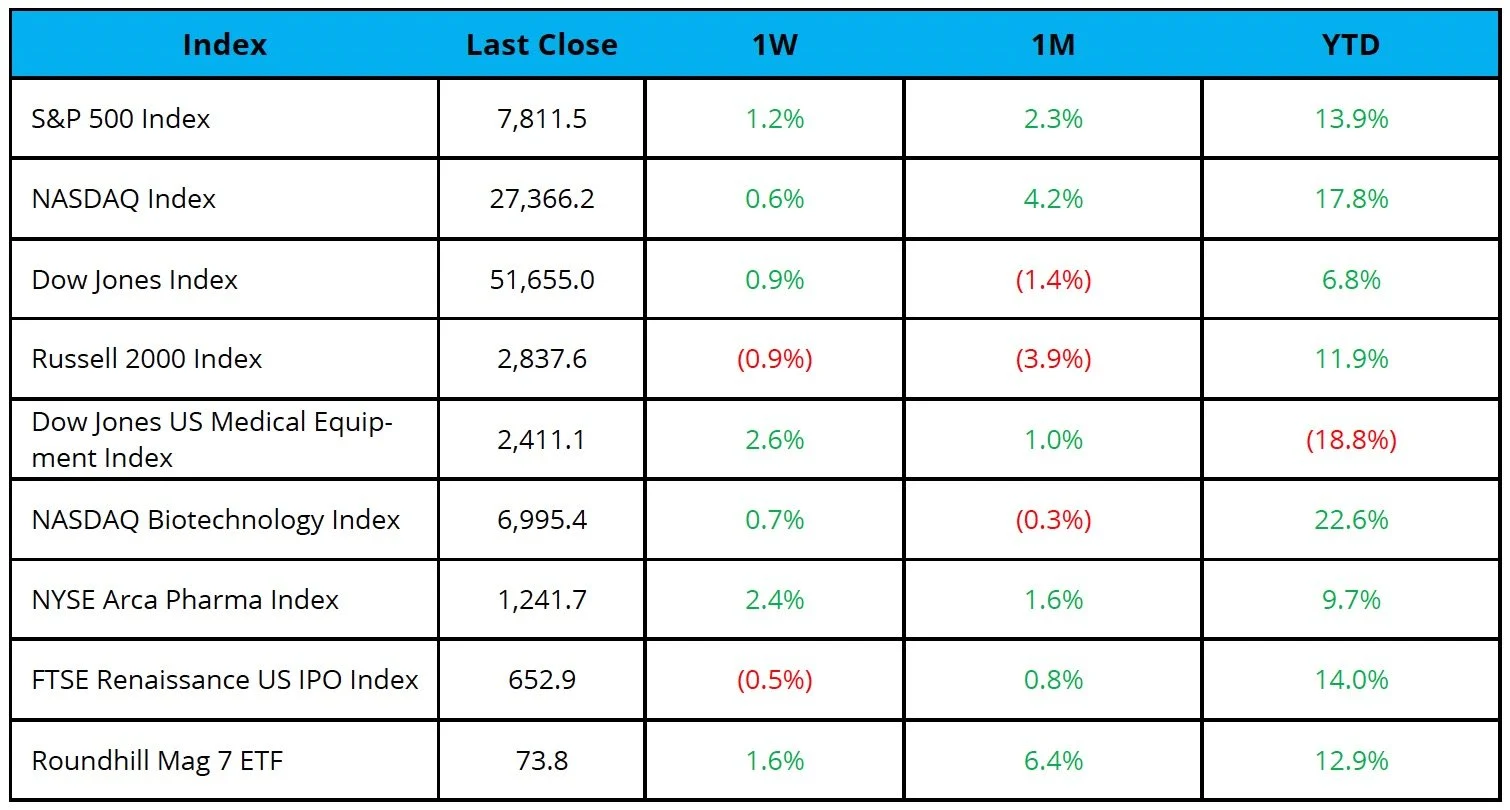
The Nasdaq was up 0.6%, and the S&P 500 and Dow were up 1.2% and 0.9%, respectively, over the last week
Large-cap indices recovered, but the Russell 2000 fell 0.9%. Healthcare outperformed: the Pharma Index gained 2.4%, medical equipment 2.6% and NBI 0.7%. The uneven recovery and sharp stock-specific moves point to continued discrimination among clinical outcomes rather than a uniform sector rally.
The NYSE Pharma Index and NBI were up 2.4% and 0.7%, respectively, over the last week
Notable change in share price:
Pacira BioSciences (NASDAQ: PCRX): Shares rose 44.4% after Viatris agreed to acquire the Company for $36.50 per share in cash, or approximately $1.65B, representing a ~45% premium and adding Pacira’s marketed non-opioid pain products EXPAREL and ZILRETTA to Viatris’ portfolio.
ArriVent BioPharma (NASDAQ: AVBP): Shares fell 47.0% after the Phase 3 FURVENT trial of firmonertinib in first-line EGFR exon 20 insertion-mutant NSCLC failed to meet its primary progression-free survival endpoint, with neither tested dose demonstrating a statistically significant improvement over chemotherapy.
Vaxcyte (NASDAQ: PCVX): Shares rose 30.7% after the Company reported positive topline Phase 3 OPUS-1 data for VAX-31, its 31-valent pneumococcal conjugate vaccine, meeting all prespecified primary endpoints and demonstrating non-inferiority across all 28 serotypes shared with Prevnar 20 and/or Capvaxive and superiority on its three unique serotypes.
Sources: Pitchbook, Biomedtracker, and CapIQ
Equity Markets
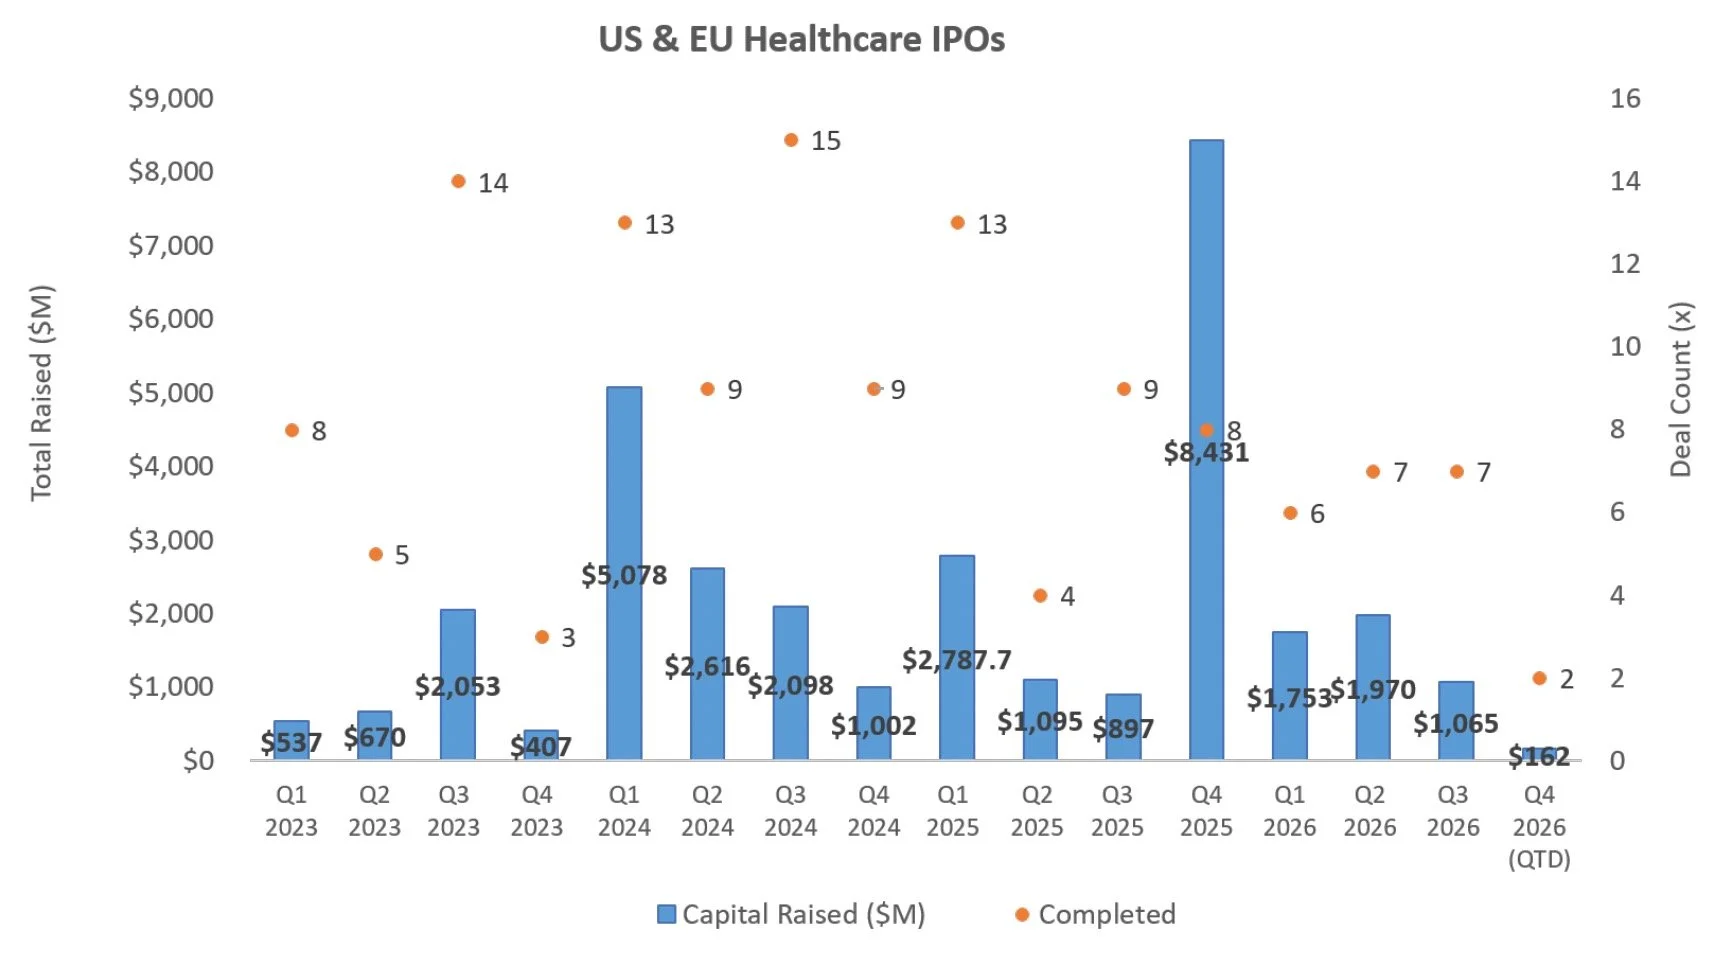
IPO
Biotech issuance resumed after a one-week pause, although deal sizes remained well below the large September offerings. TRexBio raised $116.7M and Retension $45M. The return of two issuers is encouraging; it does not yet establish stronger pricing power.
There were two healthcare IPOs priced last week totaling $161.7M:
TRexBio (NASDAQ: TRXB) raised $116.7M in its IPO to advance TRB-061, its TNFR2 agonist, through Phase 2 trials in atopic dermatitis and alopecia areata, advance TRB-071 through Phase 1 development and support working capital and general corporate purposes; Lilly had indicated interest in purchasing shares in the offering, subject to maintaining ownership below 19.9%
Retension Pharmaceuticals (NASDAQ: RTSN) raised $45M in an upsized IPO to complete RTN-001’s Phase 2b trial in uncontrolled hypertension and prepare for and advance its planned Phase 3 program, with remaining proceeds supporting general corporate purposes and operating expenses
Source: CapIQ
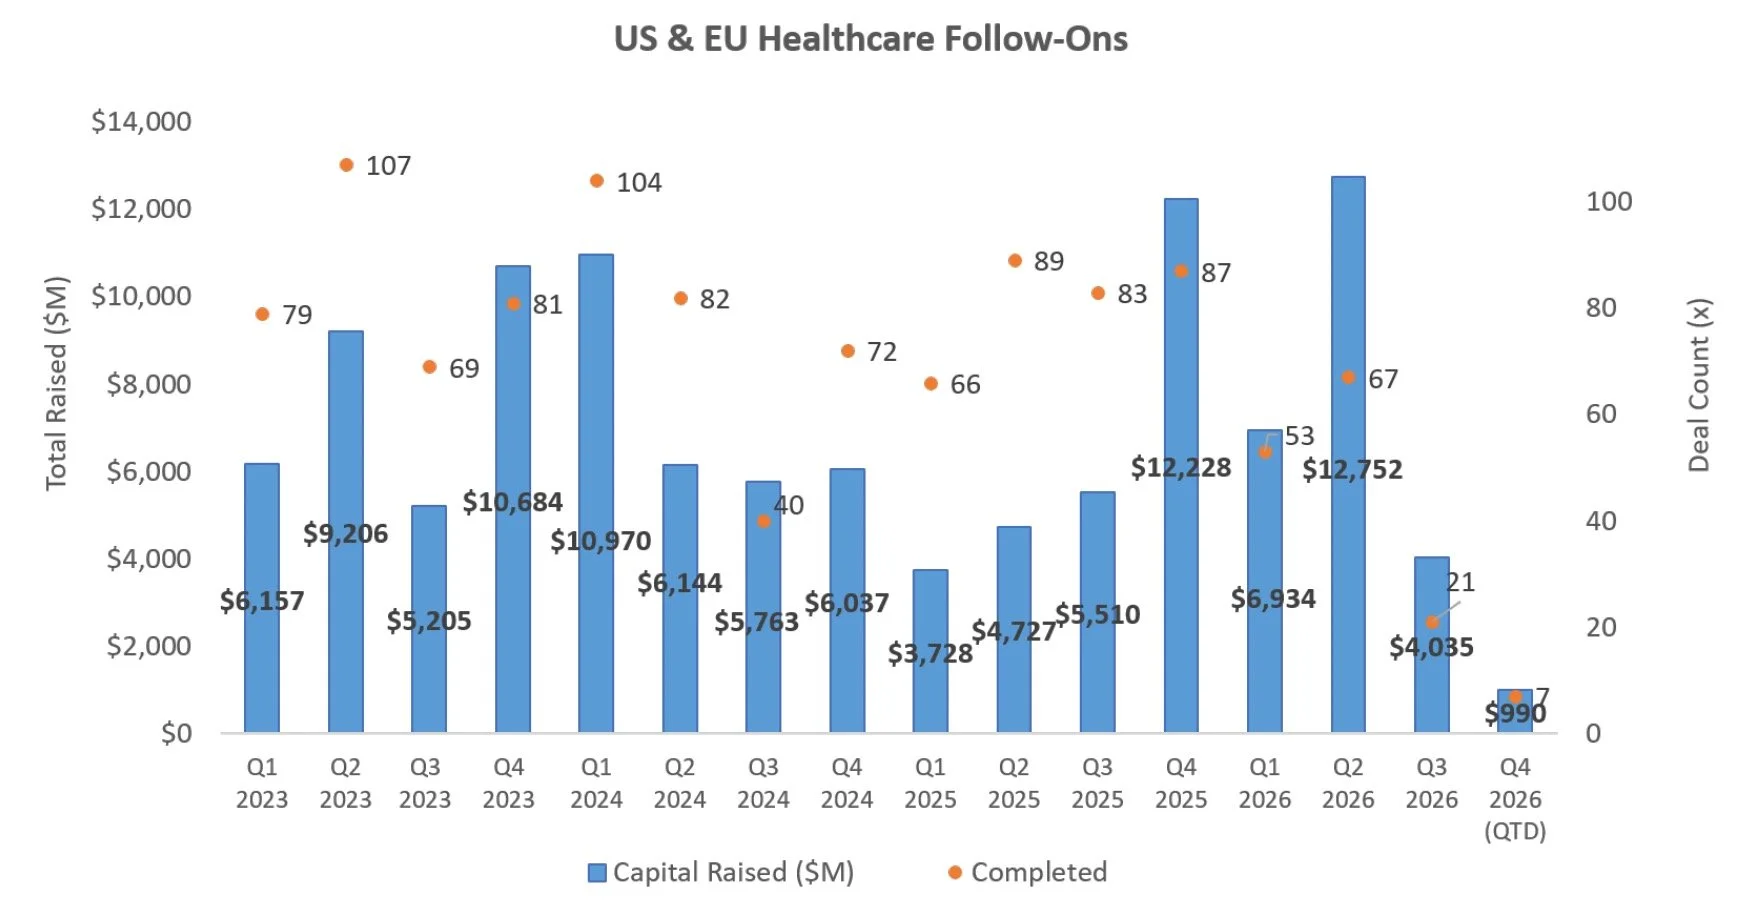
Follow On
Follow-on proceeds rose to $872.5M from $357M the prior week, led by Vaxcyte and Spyre. Vaxcyte also raised $500M in convertible notes, bringing its combined financing to $1B. Positive late-stage vaccine data enabled a sizable capital raise for clinical development, manufacturing, and launch preparation.
There were four follow-on offerings last week totaling approximately $872.5M in proceeds, including:
Vaxcyte (NASDAQ: PCVX) raised $500M in an underwritten public equity offering, concurrent with a separate $500M convertible senior notes offering, to fund Phase 3 and pediatric development of VAX-31, manufacturing scale-up and commercial readiness for a potential US adult launch, advance earlier-stage vaccine programs, and support general corporate purposes
Spyre Therapeutics (NASDAQ: SYRE)raised $350M in an underwritten public offering to advance its gastroenterology, rheumatology, and dermatology programs through preclinical and clinical development and Phase 3 readiness, including late-stage development of SPY072 in hidradenitis suppurativa, as well as support other R&D and general corporate purposes
Source: Biomedtracker
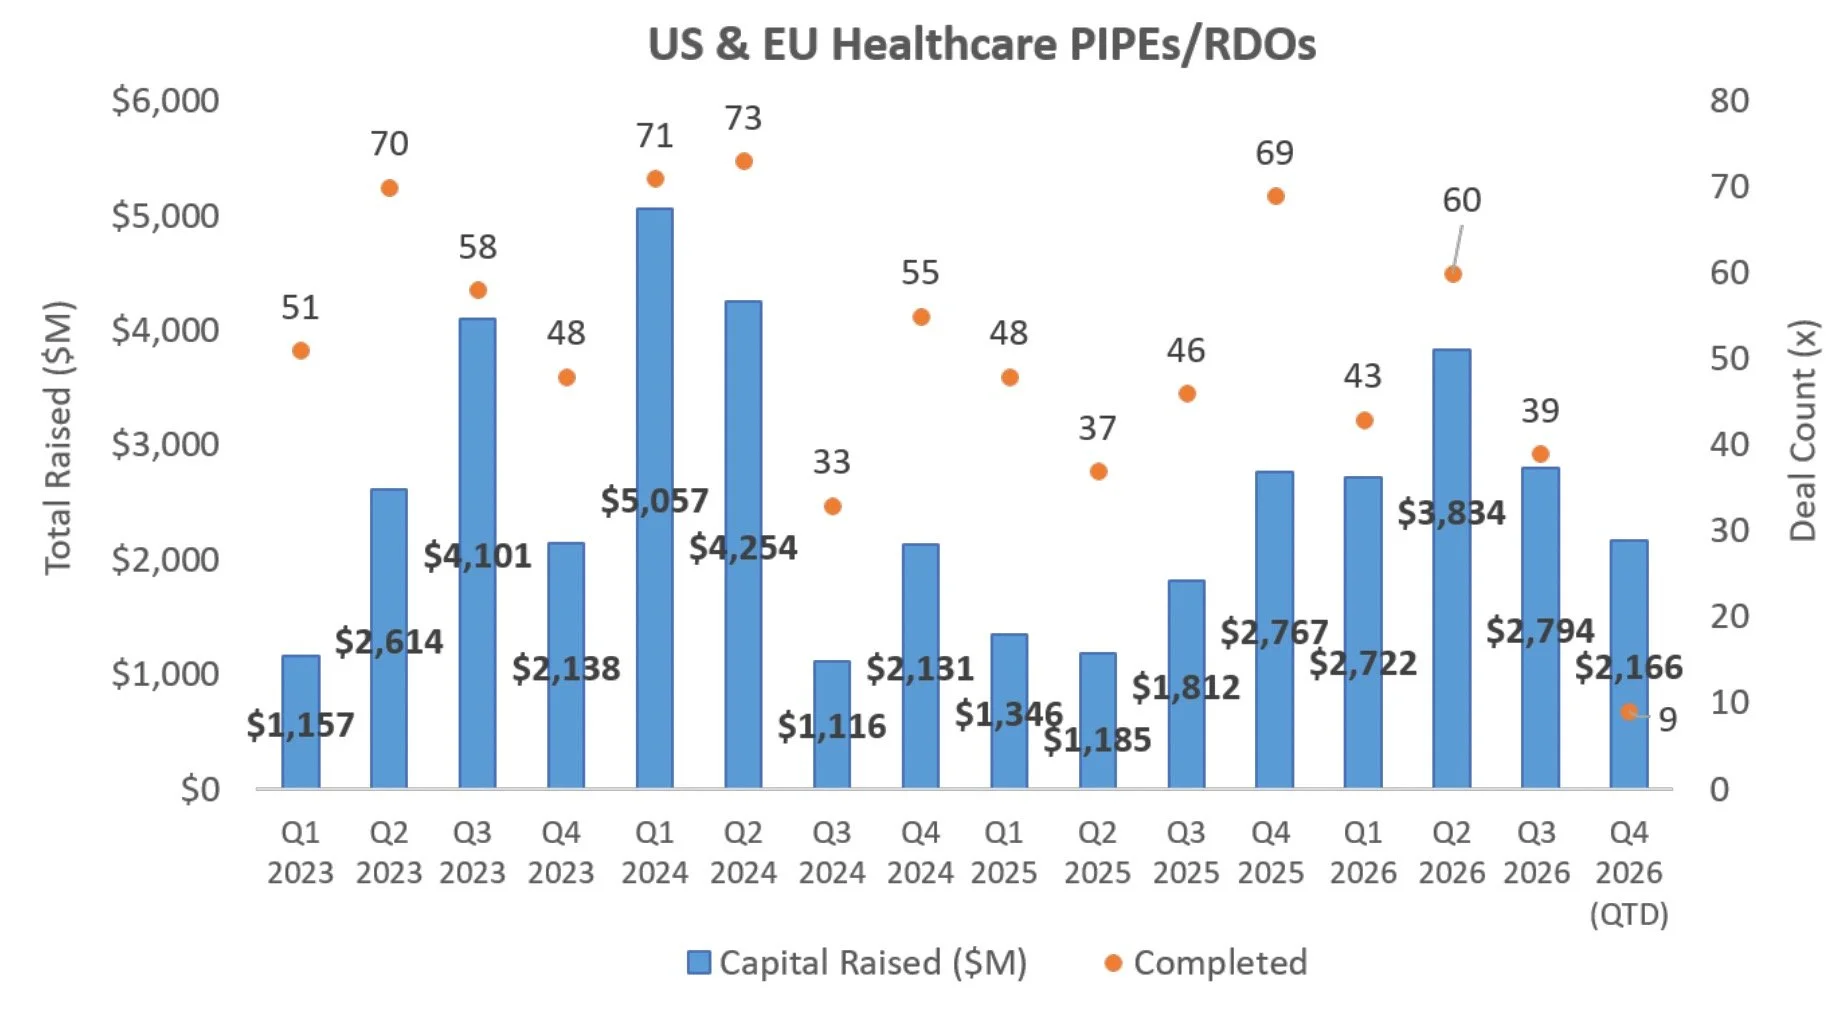
PIPE/RDO
Six transactions raised $158.5M, compared with the prior week’s $2B strategic investment in Summit. The distinction matters: conventional private placements remain modest, while specialist investors continue to support selected clinical and precision-medicine programs.
There were six PIPEs / RDOs announced last week totaling approximately $158.5M, including:
ADC Therapeutics (NYSE: ADCT) raised $86.6M in a PIPE to fund continued development of ZYNLONTA, including Phase 3 studies in diffuse large B-cell lymphoma and marginal zone lymphoma, strengthen its balance sheet, and support working capital and general corporate purposes; participating investors included Bain Capital Life Sciences, Redmile Group, TCGX, and Nantahala Capital
Atrium Therapeutics (NASDAQ: RNA) raised $50M in a private placement to fund development of its two lead precision-cardiology RNA therapeutics and other research programs, as well as working capital and general corporate purposes; participating investors included Sirenia Capital Management, Aberdeen Investments, Montanova, Sessa Capital, and Casdin Capital, among others
Licensing
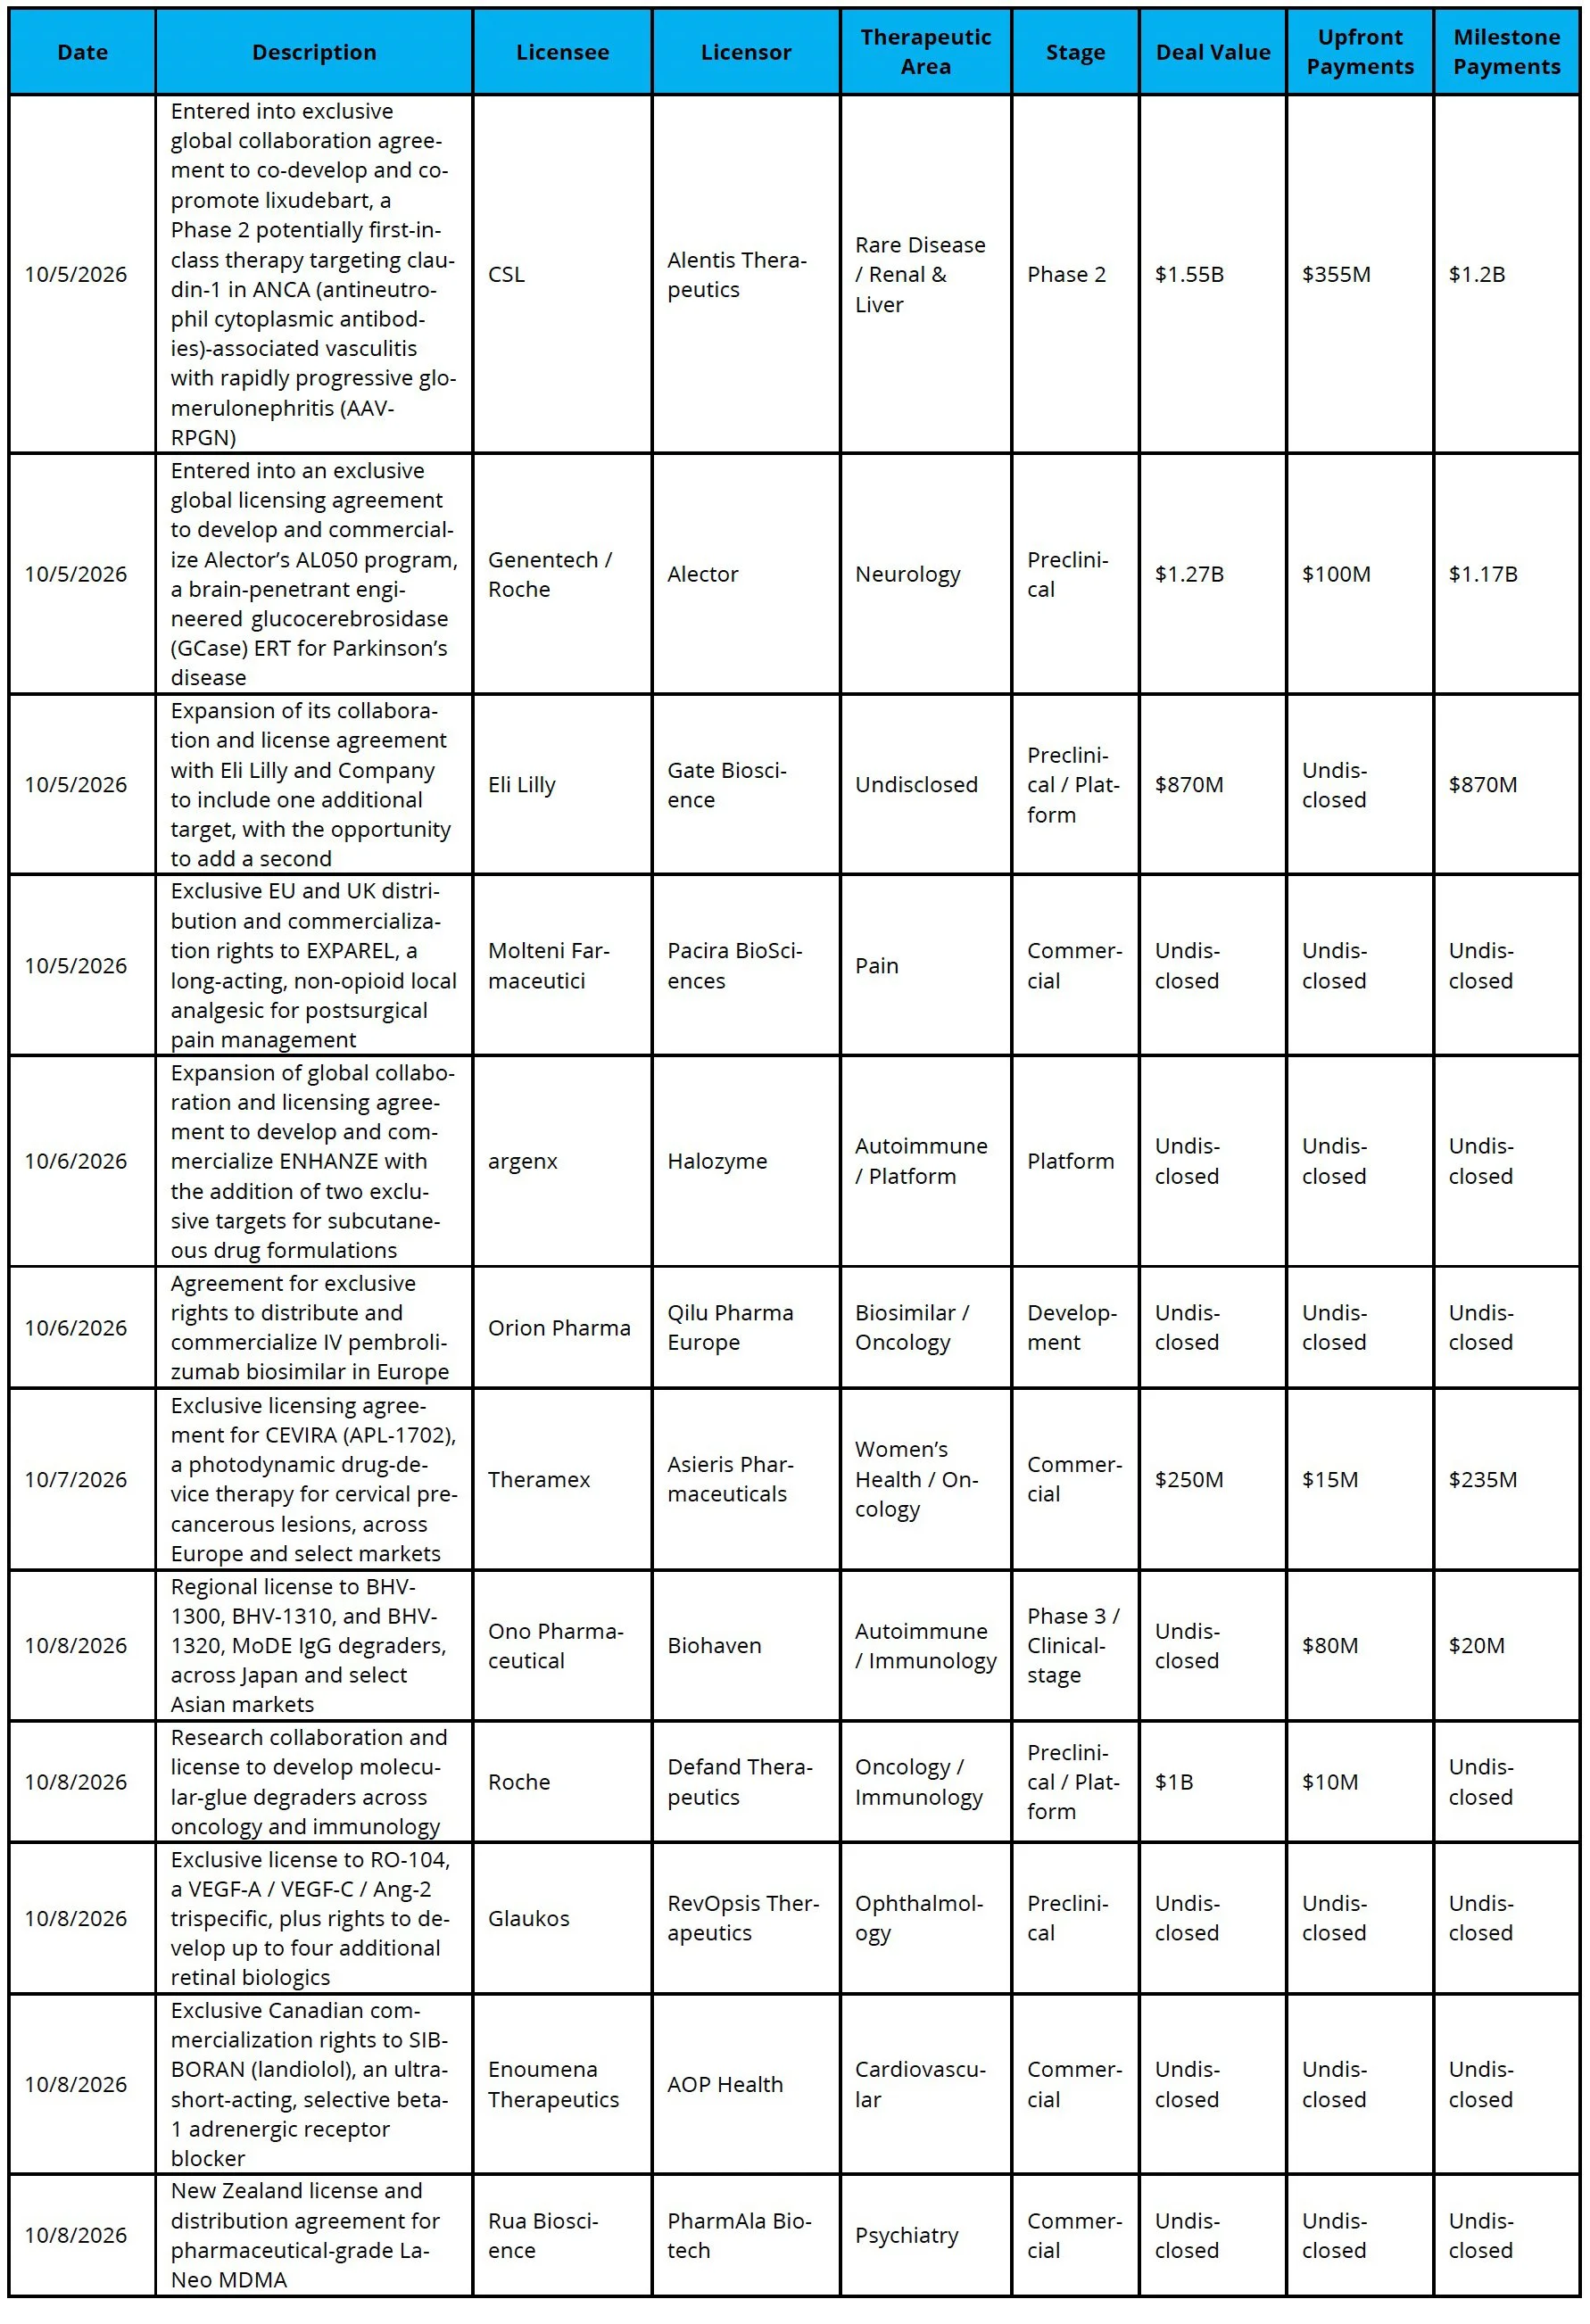
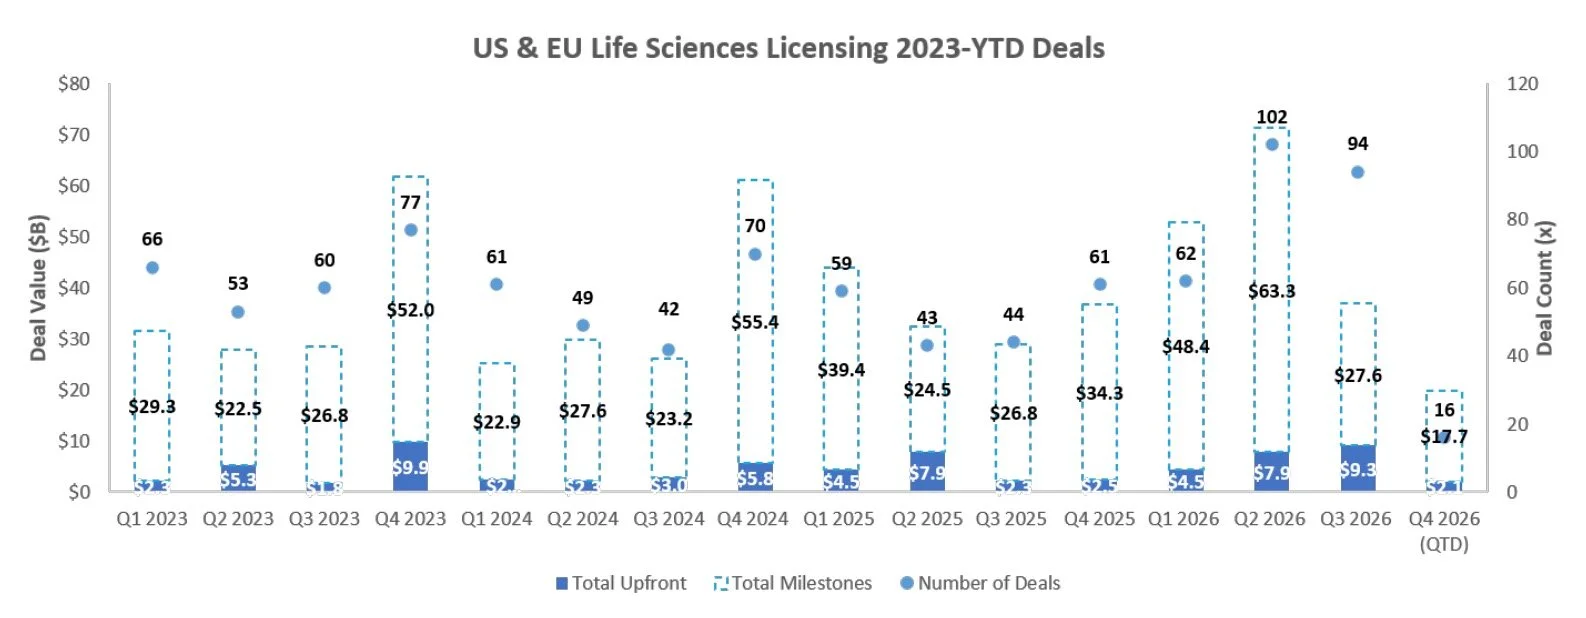
Licensing activity remained broad but shifted from last week’s unusually large upfront payments to targeted asset and platform agreements. CSL committed $355M upfront for Alentis’ Phase 2 claudin-1 program in renal and liver disease; Genentech committed $100M for Alector’s preclinical Parkinson’s program. Roche’s Defand collaboration, Lilly’s expanded Gate relationship, and several regional commercialization agreements illustrate the range of buyer objectives. The economics favor differentiated mechanisms and defined commercial rights, rather than broad platform commitments alone.
Sources: Pitchbook, Biomedtracker, and CapIQ
Sources: Pitchbook, Biomedtracker, and CapIQ
M&A
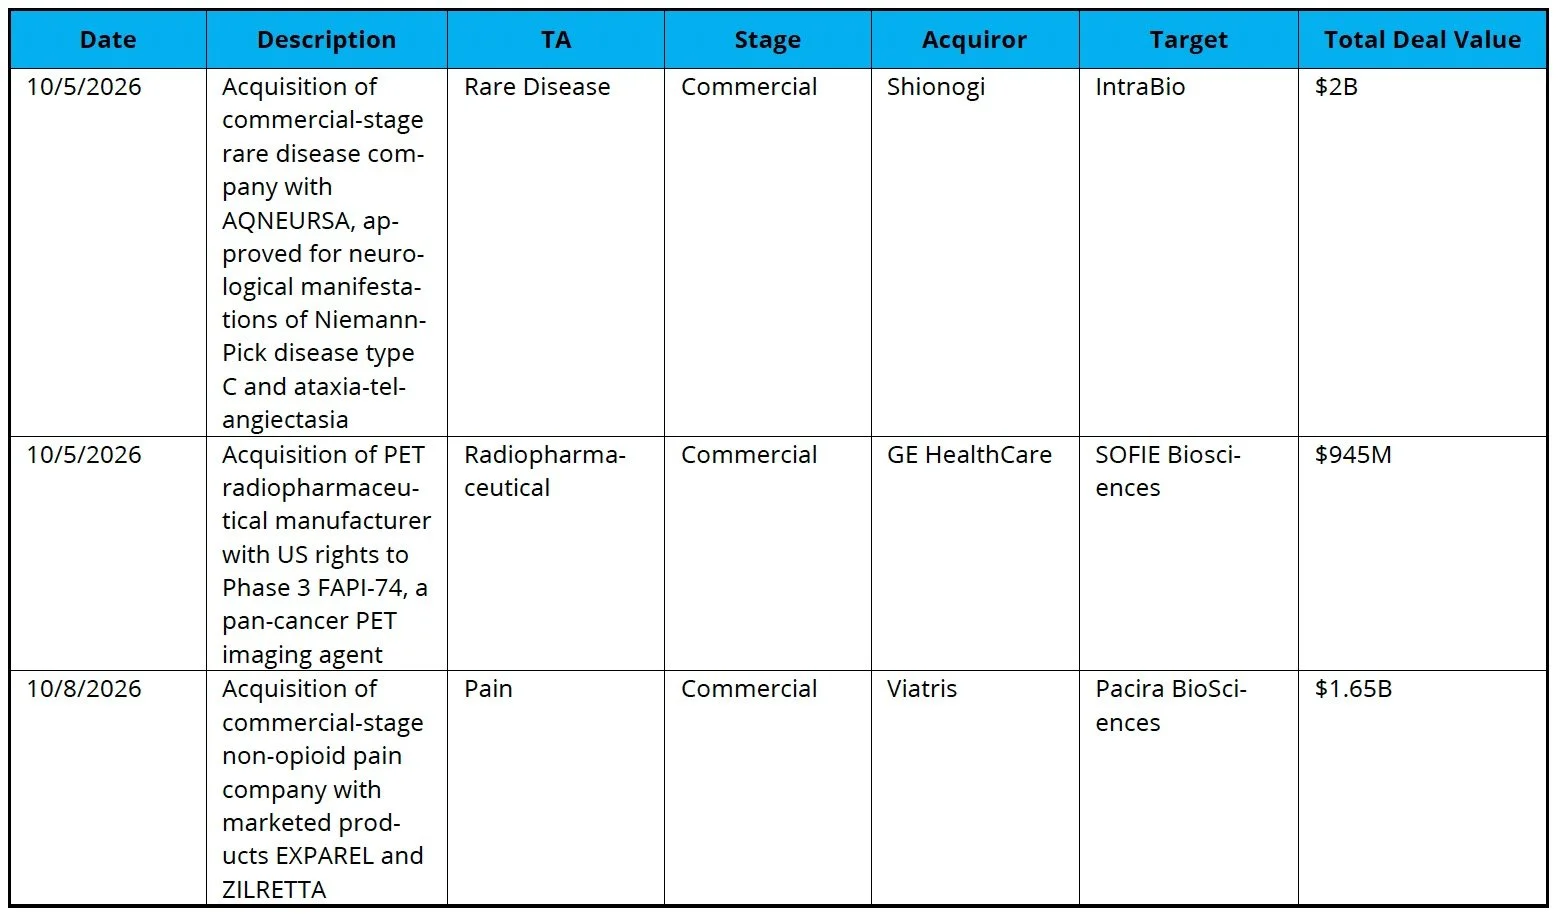
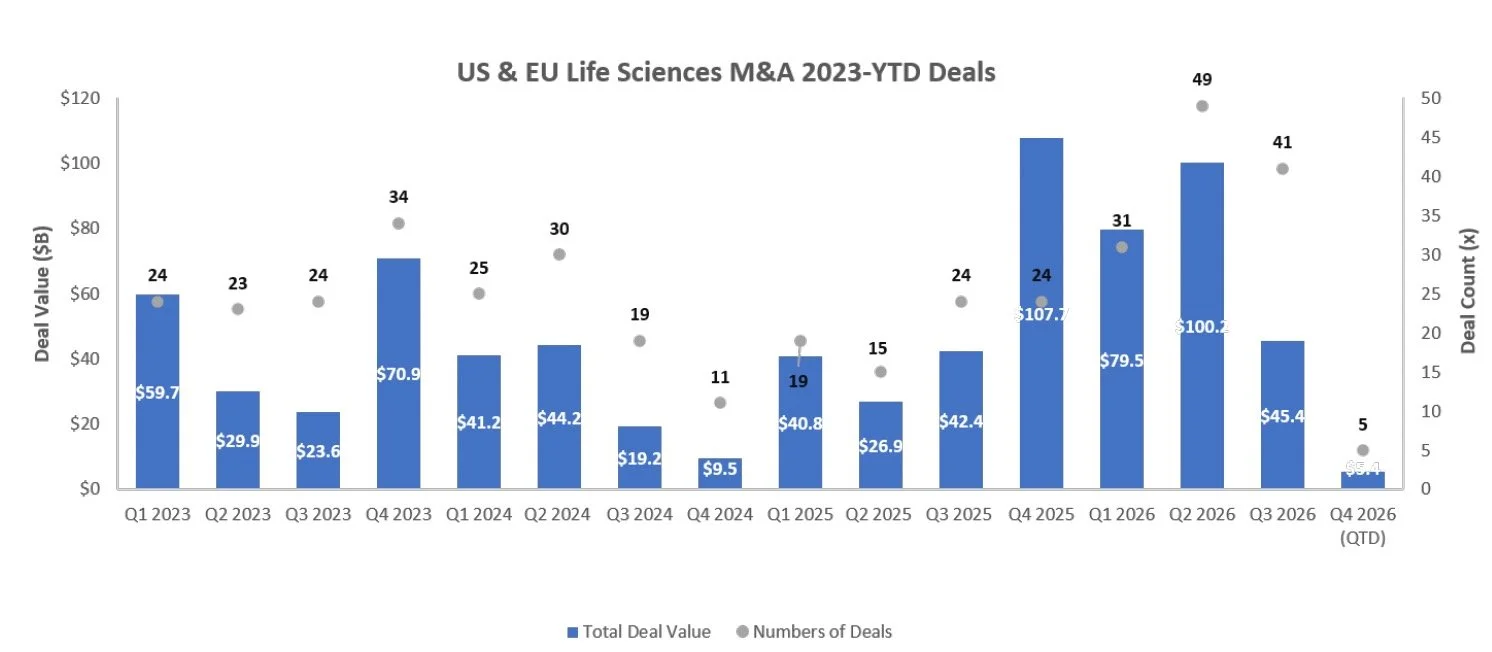
Three announced acquisitions totaled approximately $4.6B, a marked change from the prior week’s smaller capability transactions. Shionogi agreed to acquire IntraBio for $2B, adding a commercial rare-disease franchise; Viatris agreed to acquire Pacira for $1.65B, expanding its non-opioid pain portfolio. GE HealthCare’s $945M acquisition of SOFIE adds PET radiopharmaceutical manufacturing and US rights to a Phase 3 imaging agent. The common thread is control of commercial products, infrastructure, and adjacent pipeline opportunities.
Venture Financing
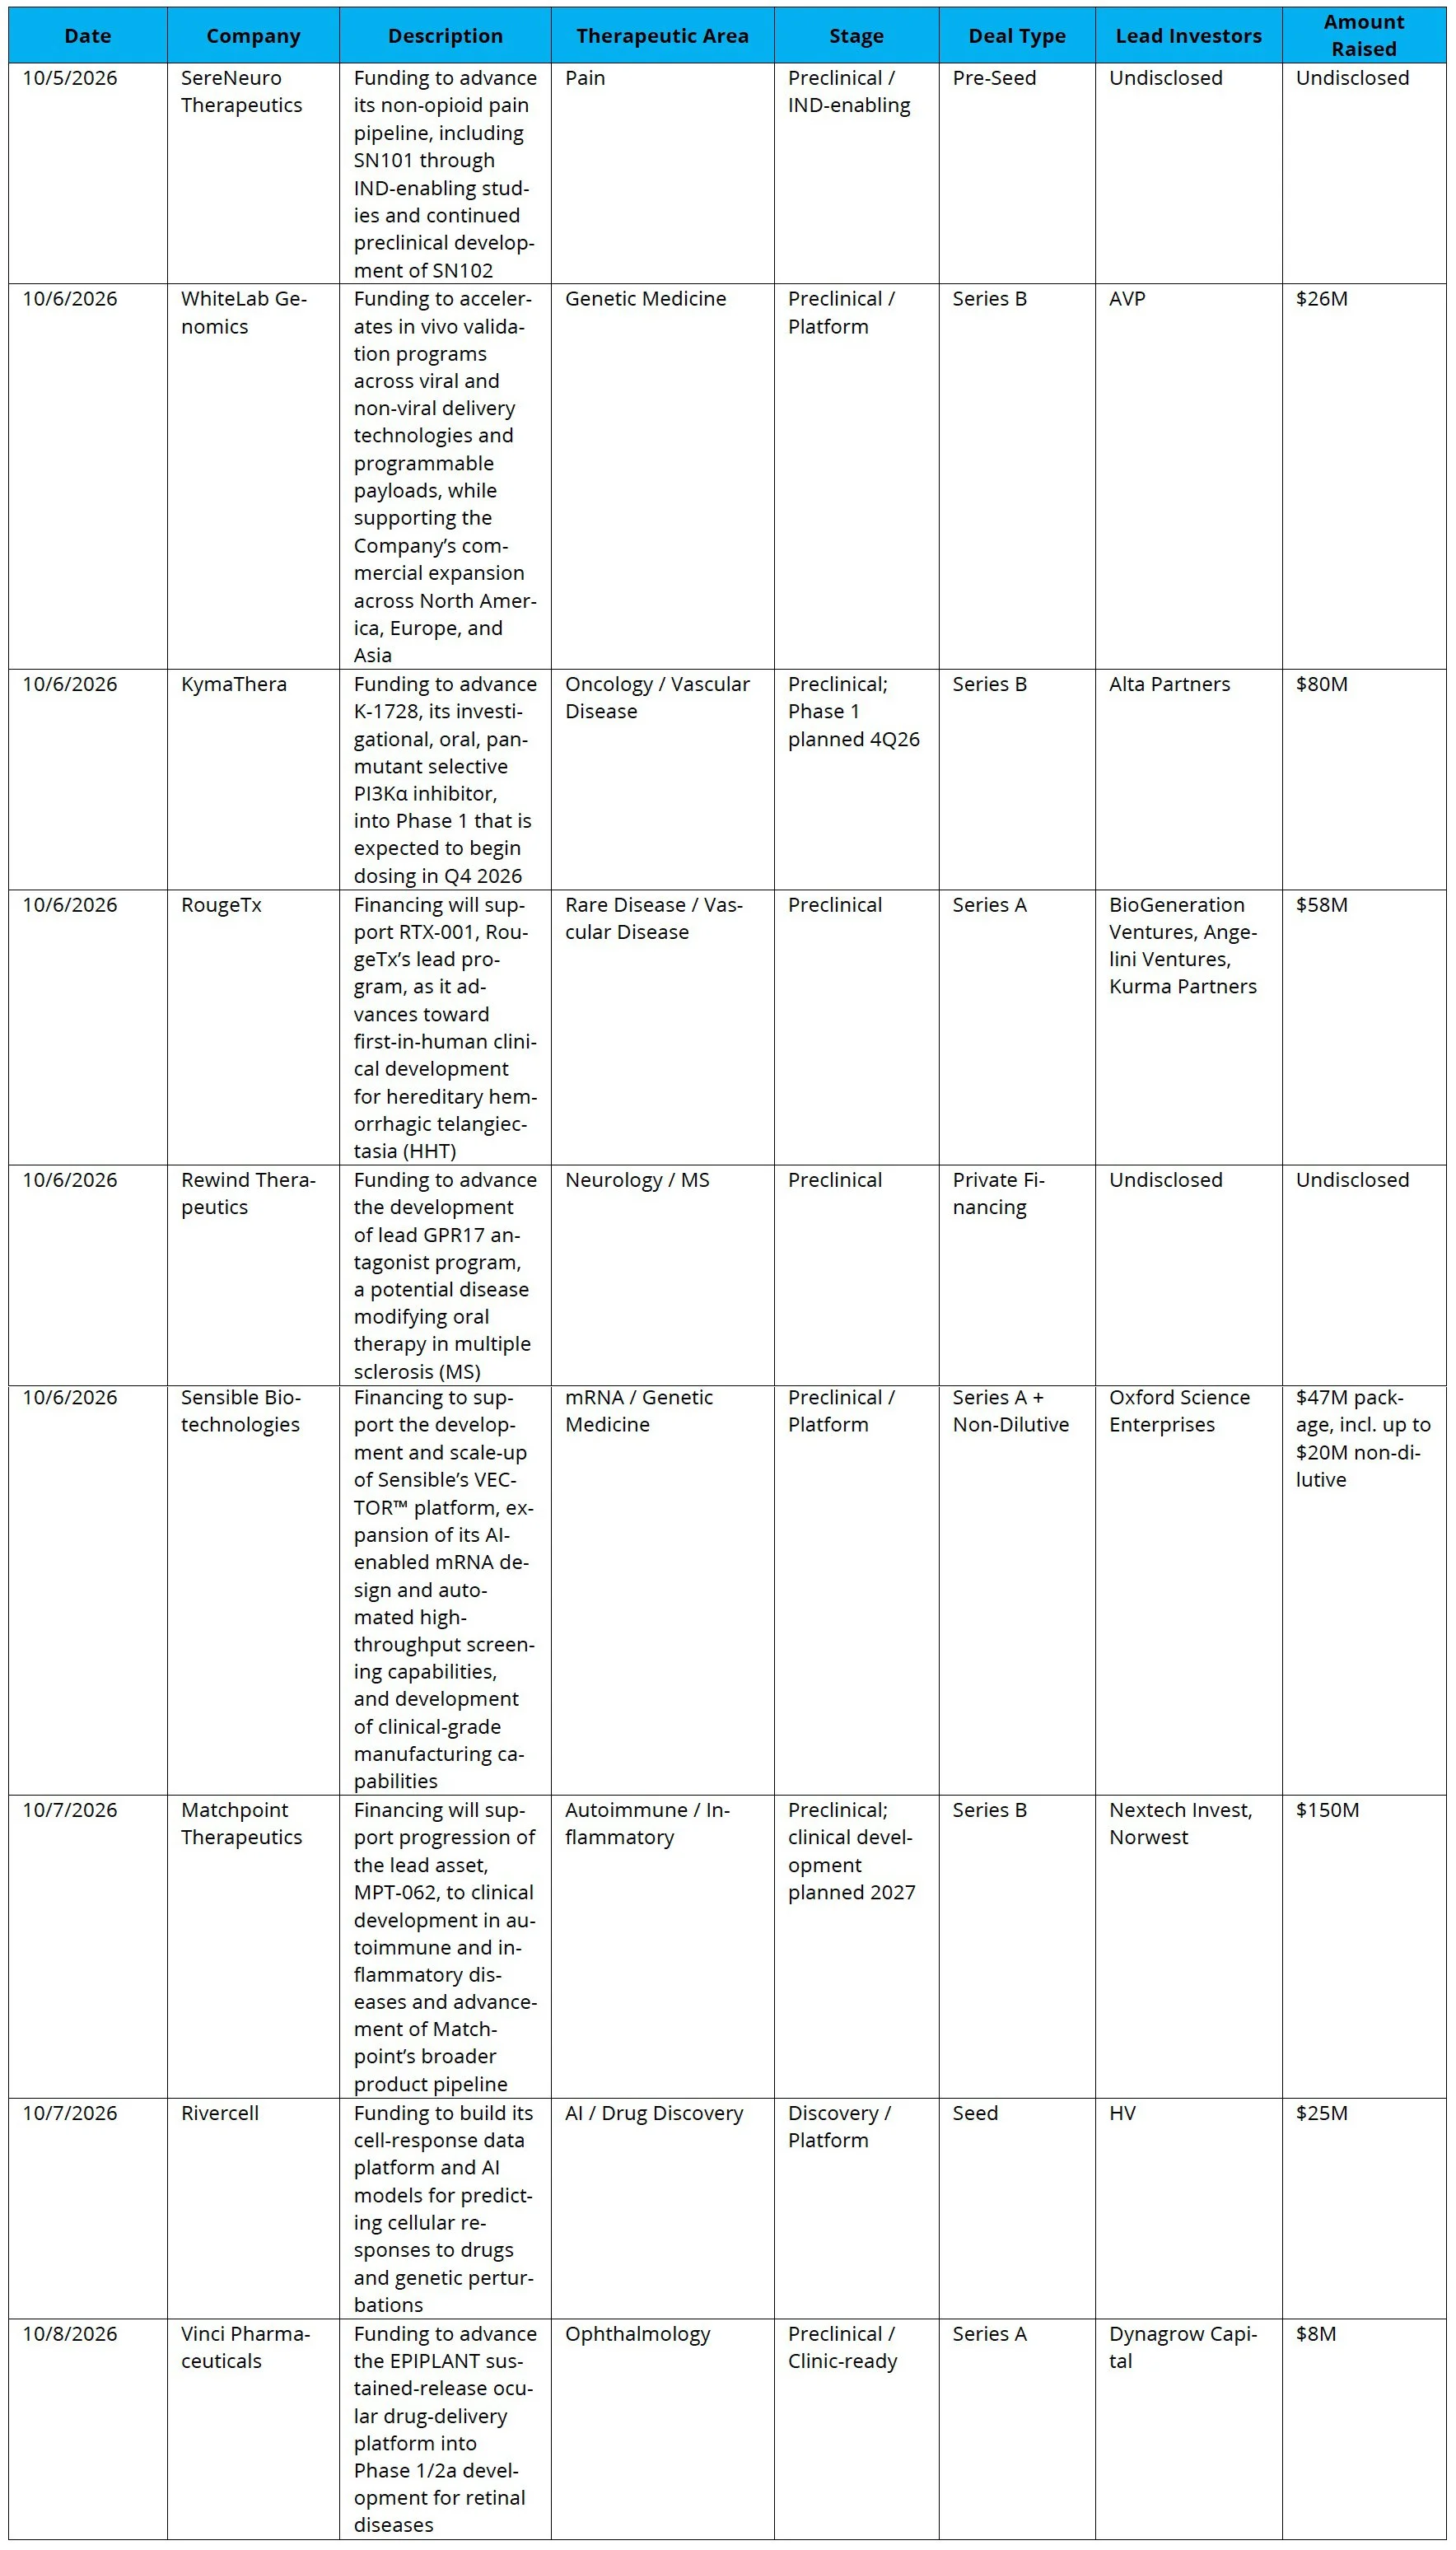
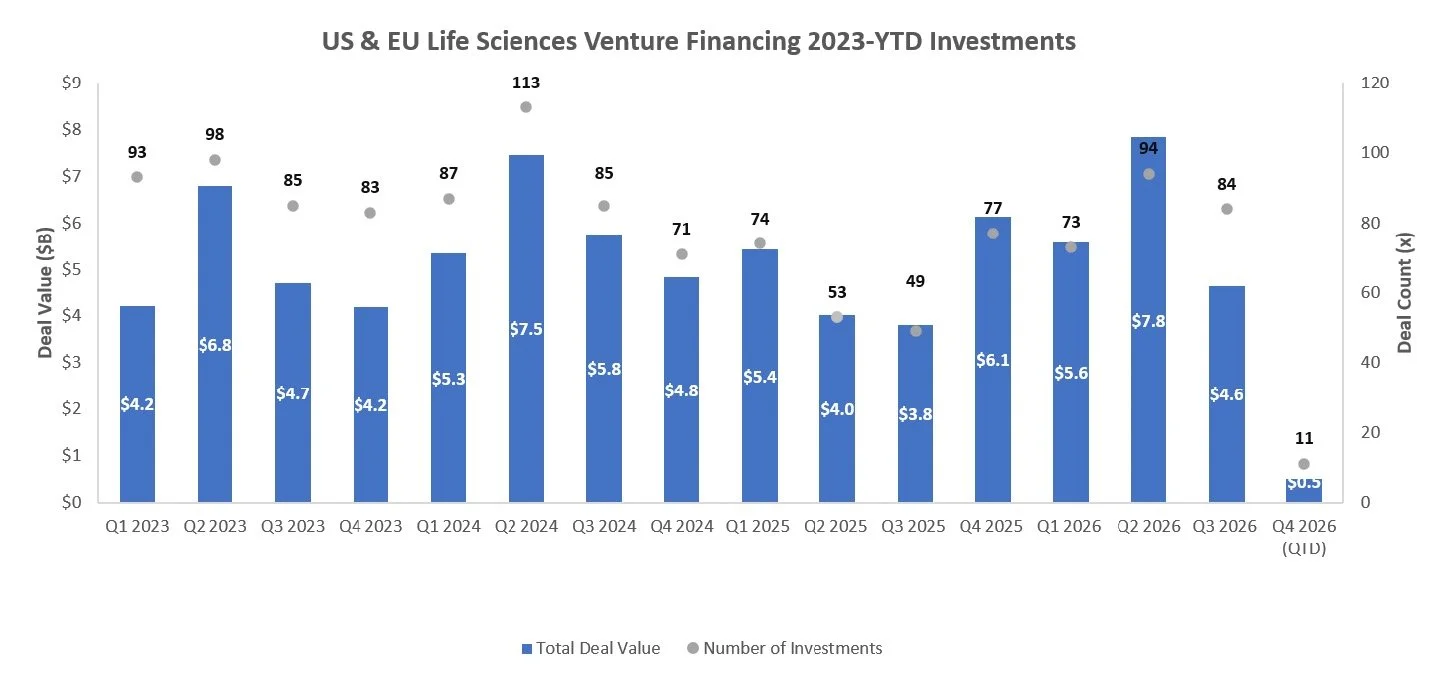
Venture funding supported both preclinical therapeutics and enabling technologies. Matchpoint raised $150M for autoimmune programs, KymaThera $80M for a PI3Kα inhibitor, and RougeTx $58M for rare vascular disease. WhiteLab raised $26M for genomic-medicine design and delivery, while Sensible announced a $47M financing package that includes up to $20M in non-dilutive support. Larger rounds remain available for programs with a defined path to clinical testing; platform financing is more selective.
The Case for a New Generation of Oral Therapies in Inflammatory Bowel Disease
Back Bay Life Science Advisors and Nimbus Therapeutics
Despite advances in the treatment of inflammatory bowel disease (IBD), many patients with moderate-to-severe ulcerative colitis (UC) and Crohn’s disease continue to experience inadequate disease control with available biologics and targeted therapies.
HEALTHCARE MARKET REPORTS ARCHIVE
-
-
-
-
-
-
-
April 17, 2026
April 24, 2026 -
-
-
-
-
-
-
-
-
-
-
-
-
-
-
About DNB Carnegie Back Bay
DNB Carnegie Back Bay drives global healthcare growth and innovation by providing a full range of strategic advisory and financing capabilities along the continuum of life science and healthcare company development. The DNB Carnegie Back Bay Healthcare Partnership is a marketing term referring to a strategic agreement between DNB Markets, Inc. and Back Bay Life Science Advisors. More information about the DNB Carnegie Back Bay Healthcare Partnership can be found here.
Securities products and services are offered in the US through DNB Carnegie, Inc., a US-registered broker-dealer and a separately incorporated subsidiary of DNB Bank ASA. DNB Carnegie, Inc. is a member of the Financial Industry Regulatory Authority (“FINRA”) and the Securities Investor Protection Corporation (“SIPC”). Securities products and services are offered in the European Economic Area through DNB Carnegie.